Skip to main content
Budget 2026: all you need to know
The Chancellor John Healey delivered his first Budget on 28 October 2026. Despite considerable speculation ahead of the Budget, there were no changes to the main rates of Capital Gains Tax (CGT) or the annual exempt amount, although changes were announced to some of the CGT reliefs available to business owners.
The Government has also reversed its previously announced proposal to restrict Cash ISA subscriptions for individuals under age 65 to £12,000 a year from April 2027. This restriction will no longer go ahead.
There was, however, a further increase to the future rates of Income Tax applying to savings and property income. A two percentage point increase had already been announced from 6 April 2027, and the Budget added a further two percentage points. As a result, from 2027/28 the basic, higher and additional rates applying to savings and property income will be 24%, 44% and 49% respectively, compared with the current 20%, 40% and 45%. The Personal Savings Allowance and Starting Rate Band remain unchanged.
The summary below highlights the Budget announcements most relevant to financial planning. We have also included important measures announced previously which are due to take effect over the coming years, to provide a consolidated overview.
Pensions
State Pension Triple Lock changes from April 2030
Under the current Triple Lock, the basic and new State Pensions increase each year by the highest of average earnings growth, CPI inflation and 2.5%. From April 2030, the mechanism will change so that increases will instead be based on the highest of CPI inflation, 2.5%, and the amount needed to ensure the state pension keeps up with average earnings growth since the introduction of the new policy.
Pensions and IHT from 6 April 2027
Most unused pension funds and pension death benefits will fall within the estate for IHT purposes for deaths occurring on or after 6 April 2027. The Budget includes a minor technical amendment allowing those administering an estate to decide whether notional pension property is included in the general component of the estate or a separate component when calculating entitlement to the reduced 36% IHT rate where sufficient assets pass to charity.
Normal Minimum Pension Age rises to 57 from 6 April 2028
Subject to protected pension ages and other exceptions. This remains an important cash-flow consideration when planning retirement or bridging the period before pension benefits become accessible.
Pension salary sacrifice NIC restriction from 6 April 2029
Only the first £2,000 a year of employee pension contributions made through salary sacrifice will retain the NIC advantage. Salary-sacrificed pension contributions above £2,000 will attract employee and employer NIC. Importantly, this is not a £2,000 restriction on salary sacrifice or pension contributions themselves. Contributions can still exceed £2,000, but the NIC advantage on the excess will be lost.
Changes announced in this Budget
Two-year rule for pension death benefits
Legislation will remove the two-year rule under which otherwise tax-free pension and lump-sum death benefits could become taxable solely because payment (or designation) was made more than two years after the scheme administrator first knew, or could reasonably have been expected to know, of the member's death. The change applies to relevant payments made on or after 28 October 2026.
Terminal illness and pension access
Legislation will allow a serious ill-health lump sum to be paid where a member can reasonably be expected to live for less than one year. It will apply to uncrystallised rights irrespective of whether the member has reached age 75. Medical evidence will also be able to be provided by an overseas registered medical practitioner where the member lives in the country in which the practitioner practises. The change takes effect from Royal Assent of Finance Bill 2026-27.
Tax on excess lump-sum death benefits
The process for taxing lump-sum death benefits exceeding the deceased's available Lump Sum and Death Benefit Allowance (LSDBA) will change. Where a member dies before age 75, the excess will no longer be treated as pension income of the individual beneficiaries. Instead, a tax charge will be raised on each beneficiary's share of the excess by reference to their marginal Income Tax rate for the year in which the lump sum was paid. The legislation will also address the interaction between Income Tax and IHT. Different elements of the measure have different effective dates, including retrospective provisions applying to relevant lump sums paid from 6 April 2024.
Defined Benefit (DB) scheme surplus payments
From 6 April 2027, DB occupational pension schemes will be able to make direct payments of surplus assets to members where permitted by the scheme rules and subject to trustee discretion and statutory conditions. Qualifying payments will be taxed as pension income.
Taxation
Savings and property income
Savings Income Tax rates increase from 6 April 2027 to:
- 24% basic rate
- 44% higher rate
- 49% additional rate
- 49% trust rate for discretionary trusts
The Personal Savings Allowance and starting rate band for savings remain unchanged.
Investment bonds:
The savings-rate changes also have implications for the taxation of life assurance business and investment bond gains. Advisers will therefore need to revisit assumptions used when comparing onshore and offshore bonds from 2027/28.
Property Income Tax rates in England, Wales and Northern Ireland will increase from 6 April 2027 to:
- 24% basic rate
- 44% higher rate
- 49% additional rate
- 49% trust rate for discretionary trusts
Income Tax ordering rules:
Consequential changes from April 2027 will affect how allowances and reliefs are allocated between different categories of income following the introduction of separate savings and property rates.
Pension Tax Allowance
- New Pension Tax Allowance from 6 April 2027: this is intended to prevent pensioners whose total income is no more than the full new State Pension from having to pay small amounts of tax through Simple Assessment. It will operate in 2027/28, 2028/29 and 2029/30.
- For 2027/28, the threshold below which the full allowance applies is £13,037 and it is fully withdrawn at £13,319. The allowance is withdrawn at £1 for every £3 of income above £13,037.
Property
- High Value Council Tax Surcharge: from April 2028, an additional charge will apply to residential properties in England valued at £2 million or more. This will be relevant for people who are property-rich but potentially income- or cash-poor in retirement.
Thresholds
- Frozen thresholds and allowances: advisers should continue to factor fiscal drag into longer-term financial planning, including the continuing freezes affecting Income Tax thresholds, the IHT nil-rate bands and ISA limits.
CGT and business owners
- Business Asset Disposal Relief (BADR): the lifetime limit will reduce from £1 million to £500,000 for qualifying disposals from 6 April 2027. This could make the timing of business disposals particularly important for qualifying clients.
- Founders' Relief: a new relief will provide a 10% CGT rate on up to £10 million of qualifying lifetime gains on eligible disposals of shares or securities from 6 April 2027. It is targeted at founders and early investors who have made a significant long-term contribution to qualifying high-growth, innovative UK companies.
- Trading Allowance: increases from £1,000 to £3,000 from 6 April 2027. The Self Assessment trading income reporting threshold will also increase to £3,000.
Employment taxation
Mandatory payrolling of Benefits in Kind, the introduction will be phased:
- Company cars and vans, car and van fuel and medical benefits from 6 April 2027
- Most other Benefits in Kind from 6 April 2028
Investments and ISAs
- Cash ISA restriction scrapped: the previously announced proposal to restrict Cash ISA subscriptions for individuals under age 65 to £12,000 a year from 6 April 2027 will no longer proceed.
- Starter Investment ISA: the Government will work with the investment industry on a possible new ISA incentive for people investing in a Stocks & Shares ISA for the first time. The detailed design has yet to be developed.
- Lifetime ISA: the withdrawal charge where a first home costs more than the existing £450,000 LISA property limit will be reduced from 25% to 20%. The 25% charge will continue to apply to other unauthorised withdrawals.
- First Time Buyer ISA: a new product will replace the Lifetime ISA for new savers. It will provide a 25% Government bonus on the final account balance, subject to a maximum bonus of £20,000, towards the purchase of a first home worth up to £450,000. Existing LISA holders will be able to continue contributing to and using their accounts under the existing rules. Launch is scheduled for April 2029.
- Help to Save: the scheme will be made permanent and eligibility widened from April 2028 to include Universal Credit claimants receiving the child element, caring element or both.
- Employee share schemes: changes will be made to both the CSOP and EMI regimes from 6 April 2027. In particular, the individual CSOP option limit will increase to £120,000, alongside other changes to the operation of the two schemes.
Other announcements include:
- A new equity-loan scheme for first-time buyers
- Increases to the National Minimum Wage and National Living Wage from April 2027
- A further freeze in fuel duty
- Changes to domestic energy charges
- Future reform of the Carer's Allowance earnings cliff edge
- The introduction of statutory parental pay for eligible self-employed individuals
If you’d like to know how the budget may impact your financial plans, why not get in touch and speak to one of our advisers today for a free initial consultation.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning, cash flow panning, trust or tax advice.
The Budget 2026: key changes to tax, pensions and ISAs
After far fewer leaks than previous years, Chancellor John Healey delivered his first Budget this afternoon.
The key changes were:
Savings and Property Tax
- An additional 2% increase to Savings and Property Tax from April 2027:
- Savings and property income tax were due to increase from 20%, 40% and 45% for basic, higher and additional rate taxpayers to 22%, 42% and 47% with effect from April 2027.
- They will now increase by an additional 2% to 24%, 44% and 49% for basic, higher and additional rate taxpayers with effect from April 2027.
- This will impact landlords and those with cash in the bank outside ISAs whose interest exceeds their Personal Savings Allowance.
- This also impacts Offshore Bond owners as Chargeable Gains are treated as savings income.
Business Asset Disposal Relief
- Which entitles qualifying business owners to a reduced capital gains tax rate of 18%, will have its lifetime limit reduced from £1,000,000 to £500,000 from April 2027. However, Founders’ Relief will entitle those who qualify, to a capital gains tax rate of 10% up to a lifetime limit of £10,000,000
Cash ISA
- The Cash ISA allowance will no longer be limited to £12,000 with effect from April 2027 for under 65s - this will remain at £20,000. Plans to tax cash and cash like investments within stocks and shares ISAs have also been scrapped.
Pension Tax Allowance
- The full State Pension will increase to £13,036 in April 2027 – it has been confirmed that pensioners over the State Pension Age with total income of £13,037 or less will not pay tax on the amount above the personal income tax allowance of £12,570. Pensioners with income between £13,037 and £13,319 (not just from State Pension) will benefit from a tapered Pension Tax Allowance on a 3:1 reducing scale. The allowance will be fully extinguished once income exceeds £13,319.
Lifetime ISA
- Penalty for accessing the Lifetime ISA to buy a house above the limit of £450,000 will be reduced from 25% to 20%. This means investors using the Lifetime ISA for its intended purpose will always at least get out what they put in (given the 25% bonus when funds are put into the ISA). The penalty will remain at 25% for other unauthorised withdrawals. A new ‘Starter ISA’ will also be introduced for first time investors, though details in respect of this were limited.
Pension administration changes
- Measures will be introduced immediately to preserve the entitlement to tax free benefits to nominated beneficiaries of pension funds, if the administration of the estate takes longer than two years from the date the pension scheme administrator is informed that the member has died. In addition, from April 2027, the collection of income tax on excess lump sum payments from pensions will be taken out of the income tax regime and a standalone tax collection process will replace it.
In terms of market reaction, at the time of writing gilt yields remained broadly unchanged and UK bank shares rose as a result of the announcement of a bank tax increase of 3% for 15 months (given this was not as severe as analysts had feared).
In summary, although the impact of the above on many people may be limited, the impact of frozen tax bandings will continue to affect millions of households. Having already been frozen until 2031, there were no further extensions to the freeze, but with UK CPI inflation currently 3.5% in September 2026, more and more taxpayers will move into higher rates of tax, whether that be 20%, 40%, 45% or 60%, even if they only receive inflationary increases to their pay.
The Budget was mixed news for savers, with the proposed reduction in the Cash ISA allowance being scrapped, but the tax on savings will now increase by 4% in April 2027. For business owners, the lifetime limit for Business Asset Disposal Relief being reduced to £500,000 is disappointing, but Founders’ Relief giving those who are entitled to the relief a reduced rate of 10% up to £10,000,000 will be welcomed. Landlords will be disappointed to see the tax they pay on rental income increasing by 4% (rather than 2%) in April, but rumoured increases to the standard rates of capital gains tax did not materialise.
To understand how the changes affect your financial plan, please get in touch for a free initial consultation to see if we can help.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning or tax advice.
Can you enjoy your retirement wealth and still leave an inheritance?
The debate around what point in your life to enjoy your hard-earned savings has sparked plenty of discussion in recent years, helped by the popularity of Bill Perkins’ book Die With Zero. Despite the title, the concept isn't about spending every last penny before you die but rather making the most of your wealth while you can.
After spending your working life, and a considerable amount of time, building up your wealth, it's worth considering whether you could be enjoying more of that wealth now while you still have your health. If you’re also planning on leaving something for your loved ones, it can be difficult to strike the balance and know when it’s the right time to start.
Arrange your free initial consultation
But how do you know when it’s the right time?
When you've spent years saving towards retirement, it's tempting to keep going until you've reached a particular figure. Perhaps you're waiting for your pension to reach a certain value or want to see your investments grow a little further before you feel comfortable drawing on them.
You may have a healthy pension and substantial savings but still feel uneasy about the prospect of spending them. This is completely normal. After all, you're moving away from a regular income and into a period of life where the money you've accumulated will need to last for the rest of your life.
However, some experiences have an expiry date and waiting too long can mean you may miss out. If you've always wanted to travel extensively, you may get considerably more enjoyment from doing so in your early retirement years, while you're fit and healthy. Equally, retiring a few years earlier might allow you to spend more time with your family, and young grandchildren, rather than continuing to work towards a savings target you may already have exceeded.
This is where understanding how much you actually need becomes important. Once you have a clearer picture of what your retirement might cost, you can start making decisions around what you want to do, rather than simply how much you want to accumulate.
Making the most of your money while you can
One of the most interesting concepts from Die With Zero is the idea of a 'memory dividend'. The experiences you enjoy today can continue to bring happiness for years to come through the memories they create. And those memories aren't necessarily just yours; they can be shared with your family and loved ones too.
Whether it's taking your family on a memorable holiday, helping your children onto the property ladder or spending more time with your grandchildren, the benefits of using your wealth can extend well beyond the initial experience.
Of course, perhaps the greatest difficulty with retirement planning is that none of us knows exactly how long our money will need to last or how much we're going to need.
We often find that people have a fairly good idea of what they've saved but are less certain about how much they can comfortably afford to spend.
Without that reassurance, it's understandable that you might hold back, even when you could potentially afford to enjoy more of your wealth or be more generous with those around you.
This is where cash flow planning can be particularly valuable.
How cash flow planning can help
At The Private Office, we use cash flow forecasting to help you understand what your finances could look like throughout retirement, taking into account your current assets, expected income and future spending.
By building a picture of your finances over time, we can explore what might happen as your spending and earning circumstances change.
For example, you might be considering giving your children £100,000 towards a property purchase. Cash flow planning can help illustrate how that decision could affect your retirement finances, including how much you might have left later in life.
We can also consider different investment returns, inflation assumptions and unexpected expenses to see how your plans might hold up if circumstances don't work out quite as expected.
Sometimes the results can be surprising. You may discover that you've been unnecessarily cautious and could afford to spend considerably more. Or the forecasts may show that making a large gift now could leave you with less financial security than you're comfortable with.
These forecasts aren't guarantees, of course, and should be reviewed regularly. But they can provide a much clearer basis for making important financial decisions.
Once you have a clearer understanding of how much you need to fund your own retirement, you can also explore whether any surplus wealth could be passed on to loved ones sooner, rather than waiting until your legacy.
Could a living inheritance make more sense?
For many people, leaving something behind for their family is just as important as enjoying their retirement. yet there's a growing argument for passing on some of that wealth while you're still alive. In fact, we ran a survey recently with over 2,000 respondents and found that 81% believe parents or grandparents should help younger generations financially during their lifetime, rather than simply leaving an inheritance when they die.
Consider how much more useful an inheritance might be to your children when they're buying their first home or raising a young family, rather than receiving it much later in life when they may already be financially secure. Our survey also found that 71% believe financial support should be given early, when it can make the biggest impact.
There's something quite rewarding about seeing your money make a difference. Seeing your contribution to their life with your own eyes means you get to share in the benefits of your generosity, and it can be very fulfilling.
Of course, you might prefer to support a charity or cause that's particularly important to you. Making donations during your lifetime means you can see how your contribution is being used, which may be just as meaningful as leaving a charitable gift in your will.
What about inheritance tax?
Passing on wealth during your lifetime can also help with inheritance tax planning, although there are rules to consider before making substantial gifts.
You can currently give away £3,000 each tax year using your annual gift exemption, with any unused allowance carried forward for one tax year. Larger gifts may also fall outside your estate for inheritance tax purposes if you survive for seven years after making them, known as the 7 year rule in inheritance tax.
If you have surplus income, you may be able to make regular gifts without them forming part of your estate, provided they meet HMRC's conditions.
The wider inheritance tax position is becoming increasingly relevant too. The standard inheritance tax nil rate band, which is the amount you can pass on before inheritance tax becomes payable, remains frozen at £325,000 until April 2031. There is an additional residence nil rate band of up to £175,000 available when you pass your home to direct descendants, subject to certain conditions. With these thresholds remaining frozen while property prices and other asset values increase, more families could find themselves facing an inheritance tax liability.
And from April 2027, most unused defined contribution pension funds and pension death benefits will be included within the value of an estate for inheritance tax purposes. This is a significant change for anyone who has been planning to leave their pension untouched to pass on to the next generation.
However, before giving money away, you need to be comfortable that you won't need it yourself. Once an outright gift has been made, you generally can't simply ask for it back if your circumstances change.
Finding the right balance
There's no particular amount you should aim to leave behind when you die. Some people are perfectly comfortable spending most of their wealth during retirement, while others take great satisfaction in knowing they'll be able to leave a substantial inheritance.
You might also find that your priorities change as you get older, particularly as your family circumstances evolve.
Having a financial plan gives you the opportunity to think about these choices properly, rather than continuing to save out of habit or holding back because you're worried about what the future might bring.
And if you can enjoy the retirement you've worked hard for while also seeing your wealth benefit the people and causes you care about, that seems a pretty good outcome.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate cashflow and estate planning or tax advice.
UK Inflation hits 3.5% ahead of Budget
UK Inflation (CPI) rose higher than expected in September to 3.5% according to the latest figures released from the Office for National Statistics (ONS).
With just a week until new Chancellor John Healey delivers his first Budget as chancellor, the new inflation figures and the subsequent expectation of a base rate hike are adding pressure. That said, unemployment in August 2026 fell to 4.7% from 4.9% in July, according to the ONS, where 5% was expected, so the overall picture is mixed in the lead up.
Reacting to the figures, Healey claimed "conflicts in the Middle East and Europe" were to blame for rising prices, adding that his Budget next week would give families and businesses "breathing space".
Economists had expected the consumer prices index (CPI) to rise to 3.4%, meaning inflation exceeded expectations by 0.1%. This may not seem like a lot, but it's important to remember that the predicted 3.4% was already a bad sign for consumers, as it is still well above the Bank of England’s 2% target.
For those on the state pension waiting on the final part of the triple lock to see what their pension increase will be, there will be no change, however. With all three elements of the triple lock now received (inflation, wages, or 2.5%), the increase in average wages has proved to be the highest of the trio, rising at 3.9%, so the government is expected to confirm 3.9% as the rise in the state pension in April.
Why is inflation on the rise again?
Figures from the ONS revealed that rising fuel costs were the biggest contributor to September’s increase in inflation. Petrol prices climbed by an average of 8.2p per litre between August and September 2026, compared with a 0.2p decline over the same period last year.
Diesel prices also increased sharply, rising by 10.7p per litre in September 2026, against a fall of 0.4p in September 2025. The increases follow a surge in global oil and gas prices since the US and Israel launched their war Iran at the end of February, disrupting energy supplies passing through the Strait of Hormuz.
Higher fuel costs also affected air travel, with fares falling by less than is typical in September following the busy summer holiday period.
However, there was some welcome news for the chancellor, as clothing prices edged down and food price inflation held steady at 1.3%. Strong competition between supermarkets helped limit the impact of rising transport costs on food prices.
What is inflation and how is it measured?
Inflation is a measure of how the prices of goods and services have increased over time. Goods are tangible items sold to customers, such as food, while services are tasks performed for the benefit of recipients, such as a haircut. Generally, this increase is measured by considering the cost of things today compared to how much they cost a year ago. The average increase between these prices is demonstrated in the inflation rate.
Rising interest rates directly affects the cost of living. For example, if the price of a bottle of milk is £1, and inflation is increasing by 5%, then your bottle of milk will cost you 5p more. Or, in other words, the spending power of your money has decreased by 5%.
Ideally, the Government wants to keep inflation low and stable. The general mandated target for the Bank of England is 2%.
Anything significantly above or below this target is thought to cause issues for the economy and may result in pressure to increase UK base rates which would increase the costs of borrowing.
Our chartered financial advisers are expert and unbiased, meaning that they can give whole of market advice, and so are best placed to give you a plan tailored exactly to your personal financial goals.
If you’d like to know more, request a free non-committal initial consultation with one of our team or give us a call on 0333 323 9065 and get in touch.
Arrange a free initial consultation
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning or tax advice.
NS&I British Savings Bond rates increase to more than 5%
National Savings & Investments (NS&I) has increased the interest rates on its Guaranteed Growth and Guaranteed Income Bonds, also known as British Savings Bonds, for the second time within two months. The latest rates, which came into effect on 6 October, are a welcome improvement for savers looking to lock away their money for a guaranteed return. But while the increases make these accounts more competitive, there are still better rates available elsewhere.
So, what has prompted another round of increases, and should savers be tempted?
Why is NS&I increasing rates again?
Unlike standard banks and building societies, NS&I’s role is to raise money for the government in a cost-effective way, so rather than trying to get to the top of the best buy tables, it adjusts its interest rates to attract enough money to meet its net financing target. The net financing target is the amount of money it aims to raise through its savings products, after deducting the money paid out to savers.
For the 2026/27 financial year, this target has been set at £15 billion, within a range of plus or minus £4 billion, up slightly from £13 billion the year before.
However, its provisional results for the first quarter, covering April to June, show that it raised just £1 billion in net financing. That is a worryingly slow start towards its annual target, particularly given that the previous financial year delivered £12.1bn.
NS&I itself acknowledged that the first quarter's result was lower than anticipated.
As well as the rates on offer simply becoming increasingly uncompetitive, earlier in the year NS&I confirmed that there had been an issue where the estates of some deceased customers were not always repaid money from all of their accounts following a bereavement claim. It has been estimated that around 37,500 cases could have been affected, involving as much as £476 million.
It’s difficult to say how much this may have affected savers' decisions, but it’s perhaps had a more damaging effect than we may have initially thought.
Against that backdrop, further rate hikes were perhaps inevitable. If NS&I wants to attract more money, it needs to offer savers a sufficiently attractive reason to choose its accounts over the alternatives.
What are the new British Savings Bond rates?
The new issues offer fixed rates for new and existing customers over one, two, three or five years, with savers able to choose between Guaranteed Growth Bonds, which pay interest at maturity, and Guaranteed Income Bonds, which pay interest monthly.
| Product | Interest Rate |
|---|---|
| Guaranteed Growth Bonds 1-year (Issue 93) | 4.99% gross/ AER |
| Guaranteed Income Bonds 1-year (issue 93) | 4.88% gross/ 4.99% AER |
| Guaranteed Growth Bonds 2-year (issue 81) | 5.07% gross/ AER |
| Guaranteed Income Bonds 2-year (issue 81) | 4.96% gross/ 5.07%AER |
| Guaranteed Growth Bonds 3-year (issue 83) | 5.10% gross/ AER |
| Guaranteed Income Bonds 3-year (issue 83) | 4.99% gross/ 5.10% AER |
| Guaranteed Growth Bonds 5-year (issue 75) | 5.17% gross/ AER |
| Guaranteed Growth Bonds 5-year (issue 75) | 5.06% gross/ 5.17% AER |
While it is encouraging to see rates improving, as ever savers should not assume that an increase automatically makes an account one of the best options available.
Can you get a better rate elsewhere?
The short answer is yes. If you are prepared to shop around, there are higher rates available across all four fixed terms.
For example, based on the rates available at the time of writing, Close Brothers Savings and Union Bank of India UK are both offering 5.12% on a 1-year bond, while Oxbury Bank pays 5.21% over two years. Chetwood Bank offers 5.23% over three years, and GB Bank pays 5.37% over five years.
To put that into perspective, on a £50,000 deposit, the difference between NS&I's 1-year Guaranteed Growth Bond rate of 4.99% AER and the 5.12% with Close Brothers would be £65 over a year.
Over a longer period, the difference can become more significant. On a £50,000 deposit, a rate of 5.37% produce £2,685 in interest over a year (before the deduction of tax), compared with £2,585 at NS&I’s 5-year rate of 5.17%. That’s a difference of £100 in the first year alone. Over the full 5-year term, the gap would grow to more than £600 if interest is compounded annually, meaning you earn interest not only on your original deposit but also on the interest added each year.
Of course, the best account for you will depend on more than just the headline rate. Minimum and maximum deposits, the length of time you are happy to tie up your money for and accessibility of the interest all matter.
But the bottom line is, as long as the provider you are considering is part of the Financial Services Compensation Scheme (FSCS) then as long as the amount you have invested with the provider is within the limit of £120,000 per person, it’s fully protected.
Should you choose a British Savings Bond?
One of NS&I's biggest attractions is the security it offers. Unlike deposits with banks and building societies, which are protected up to the FSCS limit, NS&I savings are backed in full by HM Treasury. This means savers can hold larger cash balances without needing to spread their money across several banking licences to obtain equivalent protection.
NS&I's latest rate increases are good news, as they bring British Savings Bonds closer to the leading rates in the market. But savers should compare the options, consider how much protection they need and make sure their money is working as hard as it reasonably can.
Arrange a free initial consultation
Rates correct at the time of writing.
This article is for general information only and does not constitute individual financial advice.
The Financial Conduct Authority (FCA) does not regulate cash flow planning.
£217m left forgotten in cash ISAs
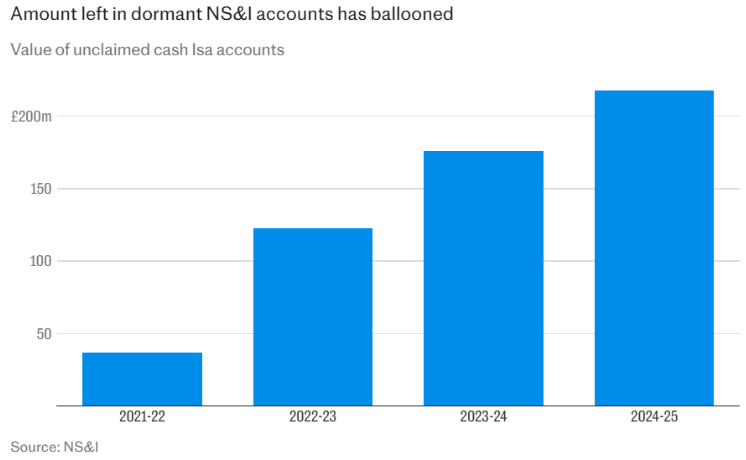
More than £217m is currently held in dormant National Savings and Investments (NS&I) cash ISA accounts, according to figures released following a freedom of information request by the Telegraph.
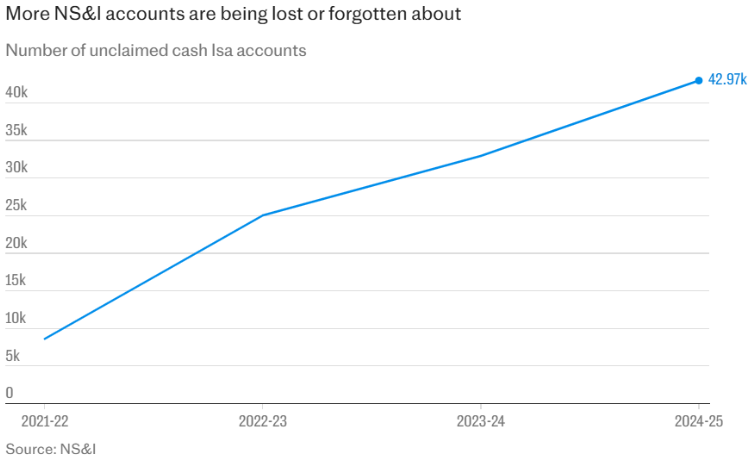
Over the past four years, the number of forgotten accounts has risen almost five-fold, with an average of £5,061 held in each inactive account.
Between 2020-21 and 2024-25, the number of dormant cash ISAs accounts climbed from 8,621 to 42,973, while the total amount held in them increased from £36.7m to £217.5m.
The Treasury-backed savings provider introduced its direct ISA accounts in 2006 and classifies them as ‘dormant’ when no transactions have taken place for 15 years. Under NS&I's procedures, account statements are no longer issued when correspondence is repeatedly returned undelivered or when these 15 years have passed without customer contact.
Although dormant accounts continue to earn interest at their usual rate, there is a risk that the money could eventually be transferred to NS&I's residual account. This holds balances from products that have matured or been withdrawn and typically pays a much lower interest rate of around 0.25%.
The figures also revealed that £614m was sitting in 1,117,000 postal-only savings accounts, which can only be managed through physical mail.
Savers with these investment accounts have missed out on average around £550 of potential interest.
The findings follow an admission by the state-owned savings provider in March 2026 that it had misplaced nearly £500m of customers' savings, potentially including cash ISAs. The issue came to light following an investigation by The Telegraph into delays in releasing funds to bereaved families.
The controversy ultimately resulted in the departure of Dax Harkins, who resigned after three years as NS&I's Chief Executive.
What is an ISA?
An ISA, or ‘Individual Savings Account’, is a scheme that allows anybody to hold cash, shares and unit trusts free of tax on dividends, interest and capital gains. Essentially, it’s a savings account that you don’t pay tax on.
A cash ISA is a tax-free savings account that allows people to save cash without incurring income tax on interest.
You can save up to £20,000 each tax year across ISAs and receive tax-free interest payments, so when the value of your cash ISA increases, you get to keep all of it tax-free. Though it's important to note that from 6 April 2027, the annual cash ISA allowance will fall to £12,000 for those under 65, while those aged 65 and over will continue to be able to save up to £20,000 each year.
While there is a £20,000 allowance in place for how much you can put in a year, there is not a cap on how much you can accumulate in an ISA over a lifetime.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered advisers to see how we can help.
Arrange a free initial consultation
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
Why AI should support, not replace, financial advice
Technology, and in particular Artificial Intelligence (AI), has rapidly changed the way we live and manage our finances in recent years. As a business, we are seeing more people arrive having already used AI either to search for and find us or to formulate their financial plan before talking it through with one of our financial advisers.
Arrange your free initial consultation
Our experience, so far, has been positive, as it has given us the opportunity to talk through all the questions asked and, in many cases, put questions back that haven’t been considered. This has given prospective clients the reassurance of knowing that the final recommendations have been reviewed by a qualified professional who is an expert in the field of financial advice. The adviser will take the time to understand their individual circumstances and most Importantly, as a regulated firm, any advice they then go on to take is protected. AI financial advice is currently unregulated and offers no redress or protection to consumers.
Understanding how best to use AI for financial advice is vital
AI can help you prepare for conversations, reinforce your understanding and ask better questions. Used badly, it can give you misplaced confidence in an answer that may be outdated or simply wrong, a common issue with AI where they ‘hallucinate’, confidently providing incorrect information and presenting it as fact.
That distinction matters because more people are now using AI to help with financial decisions. The industry regulator, the FCA, recently did a review and found that around one in five UK adults are open to AI making financial decisions for them, while Government analysis of the same review said around 26% of people trust general purpose tools such as ChatGPT, Claude or Gemini for financial advice, despite limited awareness that formal routes to redress and compensation may not apply.
It is easy to see why AI is attractive. You can ask a question at any time, in plain English, and receive an instant answer. If you want to understand financial terms and concepts, AI can often explain the basics in a way that feels more approachable than searching through technical guidance.
For example, someone might use AI to prepare for a meeting with a financial adviser. In that sense, AI can play a helpful role. It can make you feel better informed before you sit down to make important decisions.
The challenge is that financial planning is rarely just about one question. The right answer often depends on personal context such as your income and tax position, and even things you wouldn’t always think to add like attitude to risk and future financial and life goals. If any of that context is missing, the answer can quickly become unsuitable.
That is especially important if your affairs are more complex or just bigger in monetary terms. A high earner asking about pension contributions may also need to think about annual allowance rules, tapered allowance, salary sacrifice, tax relief, cashflow, protection and inheritance tax. A simple AI answer might explain one part of the picture but miss the wider planning point.
The risk of relying on AI alone
The main risk of AI is that it can be wrong, and due to the confidence with which it will present each answer, you can never be sure when it’s accurate or wide of the mark.
Recent research from Saturn, reported by Financial Reporter and InvestmentNews, found that major AI models gave incorrect or incomplete answers to financial questions in 57% of cases. On harder questions, the error rate reportedly rose to 88% on average. The questions covered areas including pensions, mortgages, inheritance tax, retirement planning and debt management.
Those are not minor topics. A wrong answer on a pension transfer for example could have lasting financial consequences. It could mean losing guarantees or safeguarded benefits, making a decision that cannot easily be reversed or one that results in a significant tax bill.
Financial rules change regularly, and some models may rely on outdated information unless they are connected to current sources and prompted carefully. Even then, you still need to know whether the source is reliable and whether the answer applies to your personal circumstances.
This is where the difference between information and advice becomes important. AI can provide general information like definitions and explaining basic concepts. What it cannot reliably do is take responsibility for a personal recommendation that is suitable for you and your unique circumstances.
What is the Financial Conduct Authority (FCA) doing about AI and financial advice?
The FCA is looking closely at how AI could reshape retail financial services. Its Mills Review, published in July 2026, considered how AI may affect consumers, firms and markets. It recognised the potential for AI to reduce friction and help address the advice gap, but also raised questions about suitability and consumer protection.
The Government has also confirmed that the FCA is considering the impact of financial guidance and advice like outputs produced by general purpose large language models. This matters because many AI tools currently sit outside the traditional advice framework, even if the answer they provide looks and feels like advice.
The FCA says you are unlikely to have access to the Financial Ombudsman Service or Financial Services Compensation Scheme if you use a firm that is not authorised. By contrast, regulated financial services bring formal complaint routes, and FSCS may provide compensation in some circumstances if a regulated firm fails and eligible advice was unsuitable.
That protection is a key part of the advice process. It means there is accountability behind the recommendation.
Working with an adviser in an AI world
AI is a tool, and like any tool, its value depends on how you use it. Importantly here the emphasis is on you. It’s only as good as the questions you ask it to answer.
What we sometimes find when clients come to us, having used AI to prepare questions for their financial adviser, is the prospective clients don’t always fully understand what they are asking. This can create a false impression that they are already familiar with certain financial concepts. It’s better to know what has been done using AI so that we spend the right amount of time fully explaining certain terms or financial concepts, as we normally would, during an initial conversation.
When used carefully, AI can help you become a more informed client. It can help you understand the language of financial planning, gather the right personal information to come to the initial meeting with and take a more active role in decisions. It can also help you challenge assumptions and ask clearer questions.
But regulated advice still matters. A financial adviser can look at your full financial picture, understand your priorities, explain the trade-offs and provide a personal recommendation that is specifically tailored to your best interests. An adviser is also working within a regulated framework that is designed to protect you.
How AI can support you before speaking to an adviser
AI can be useful before you speak to an adviser because it can help you organise your thinking. You might ask it to explain the difference between an ISA and a pension, summarise the main questions to consider before entering into retirement planning conversations, or help you list the information an adviser may need in order to come to the meeting prepared.
This means you can arrive with a clearer sense of what matters to you, letting your adviser spend more time on the areas where professional judgement adds most value.
The important point is that AI should help you prepare for advice rather than being a substitute for the advice itself.
How AI can support you during your adviser meeting
AI can support you in the advice process, allowing you to check your understanding of the recommendation and advice to give you added confidence throughout, but it should not be the whole advice. The best outcome is found by using AI to become better informed, while relying on regulated advice when decisions are personal, complex or otherwise financially significant.
If you’ve used AI for financial advice and would like to see how our advice compares, why not give us a call for an initial conversation to see how we can help.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning or tax advice.
Budget rumours? Don't panic.
It is not long until Chancellor John Healey’s first budget on 28 October 2026 and you may be wondering if you need to take any action ahead of this.
Newspaper speculation ahead of previous budgets has been rife, with rumours that tax free cash entitlements will be reduced seeming to surface around this time every year. Some pension holders seem to have been taken in by this speculation in previous years; a recent Sky News article revealed £91.2bn was withdrawn from pensions accessed for the first time in 2025/26, up from £53.6bn in 2023/24. However, some people may be regretting their decision to take money out of their pension, given they may have moved funds from a tax free environment within their pension into a taxable environment outside it.
Arrange your free initial consultation
Pensions minister Torsten Bell clearly finds the speculation unhelpful, describing misleading stories as ‘disgraceful’ and ‘garbage’ in a recent Citywire article.
Even if there are no changes to tax free cash entitlements announced in the budget, we are getting closer to the implementation date for a big pension change that has already been announced; that defined contribution pensions will form part of estates for inheritance tax (IHT) purposes from April 2027. Pensions should be reviewed ahead of this, specifically:
- The nomination of beneficiaries for pensions - if a married couple are planning to leave their pension to their children rather than each other, this could become tax inefficient in April 2027.
- The interaction between pension nominations and wills - especially when these are not being left to the same beneficiary. As inheritance tax will be proportioned between the pension and the estate, the net amounts each beneficiary receives may change overnight on 5 April 2027.
- Gifting to charities – again the best way to do this may change. Estates benefit from a reduced inheritance tax rate of 36% when over 10% of the taxable net estate is left to charity, but pension death benefits from April may be subject to IHT and income tax, so it could be the case that leaving part of the pension to charity rather than part of the rest of the estate may become the better option.
However, those aged under 75 who are married or in civil partnership should not panic, as upon their death they can leave their pension to their spouse/civil partner under the spousal exemption and their spouse/civil partner can in turn draw from the pension tax free. Longer term however, consideration could be given if appropriate, to drawing from the pension to create excess income that can be gifted away under the regular gifts out of surplus income IHT exemption as the individual approaches age 75, at which point the tax rules change.
In terms of changes that could be announced:
- Prime Minister Andy Burnham has signposted a new ‘Your First Home’ scheme to help first time buyers get on the housing ladder.
- There are rumours that capital gains tax (CGT) could be increased. The level and timing of the increase would be important if this does happen, as there are question marks over the increased revenue that is actually raised by increasing CGT, given individuals can choose to hold onto assets and not sell them if increases to CGT rates are significant. However, if a change is announced to take effect in April 2027, this gives individuals the chance to sell assets before the higher rate kicks in which could lead to an increase in activity.
- As has been the case in previous years, the chancellor has the option to freeze tax bandings further into the future.
To summarise, Torsten Bell’s comments indicate he is hoping not to see the same level of pre-budget speculation as previous years and investors have often seen sub-optimal outcomes after making decisions based on speculation alone. Therefore, we will need to wait until after the budget to decide if any action is required as a result of any newly announced changes, alongside already known:
- Fiscal drag caused by frozen tax thresholds until 2031
- Upcoming increases to property income and savings tax rates in April 2027
- Cash ISA changes which will limit contributions from next year and mean that individuals looking to transfer their Stocks and Shares ISA into Cash ISAs must do so by April 2027
- Mansion tax due to take effect in April 2028
- Salary sacrifice National Insurance saving contribution limit of £2,000 to take effect from April 2029
If you would like to discuss the implications of the upcoming changes, please contact get in touch to see how we can help.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning, wills or tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available. Your pension income could also be affected by the interest rates at the time you take your benefits.
NS&I raises British Savings Bond rates again – but are they good enough?
Just one day after the Bank of England's Monetary Policy Committee (MPC) voted to keep the base rate on hold at 3.75% on 30th July 2026, National Savings & Investments (NS&I) announced another increase to the rates on its Guaranteed Growth and Guaranteed Income Bonds, also known as British Savings Bonds.
This is the third increase to these bonds this year and, given that the base rate was left unchanged, it may seem a little surprising. However, when you look at what has been happening in the wider savings market, the move makes perfect sense.
What are the new rates?
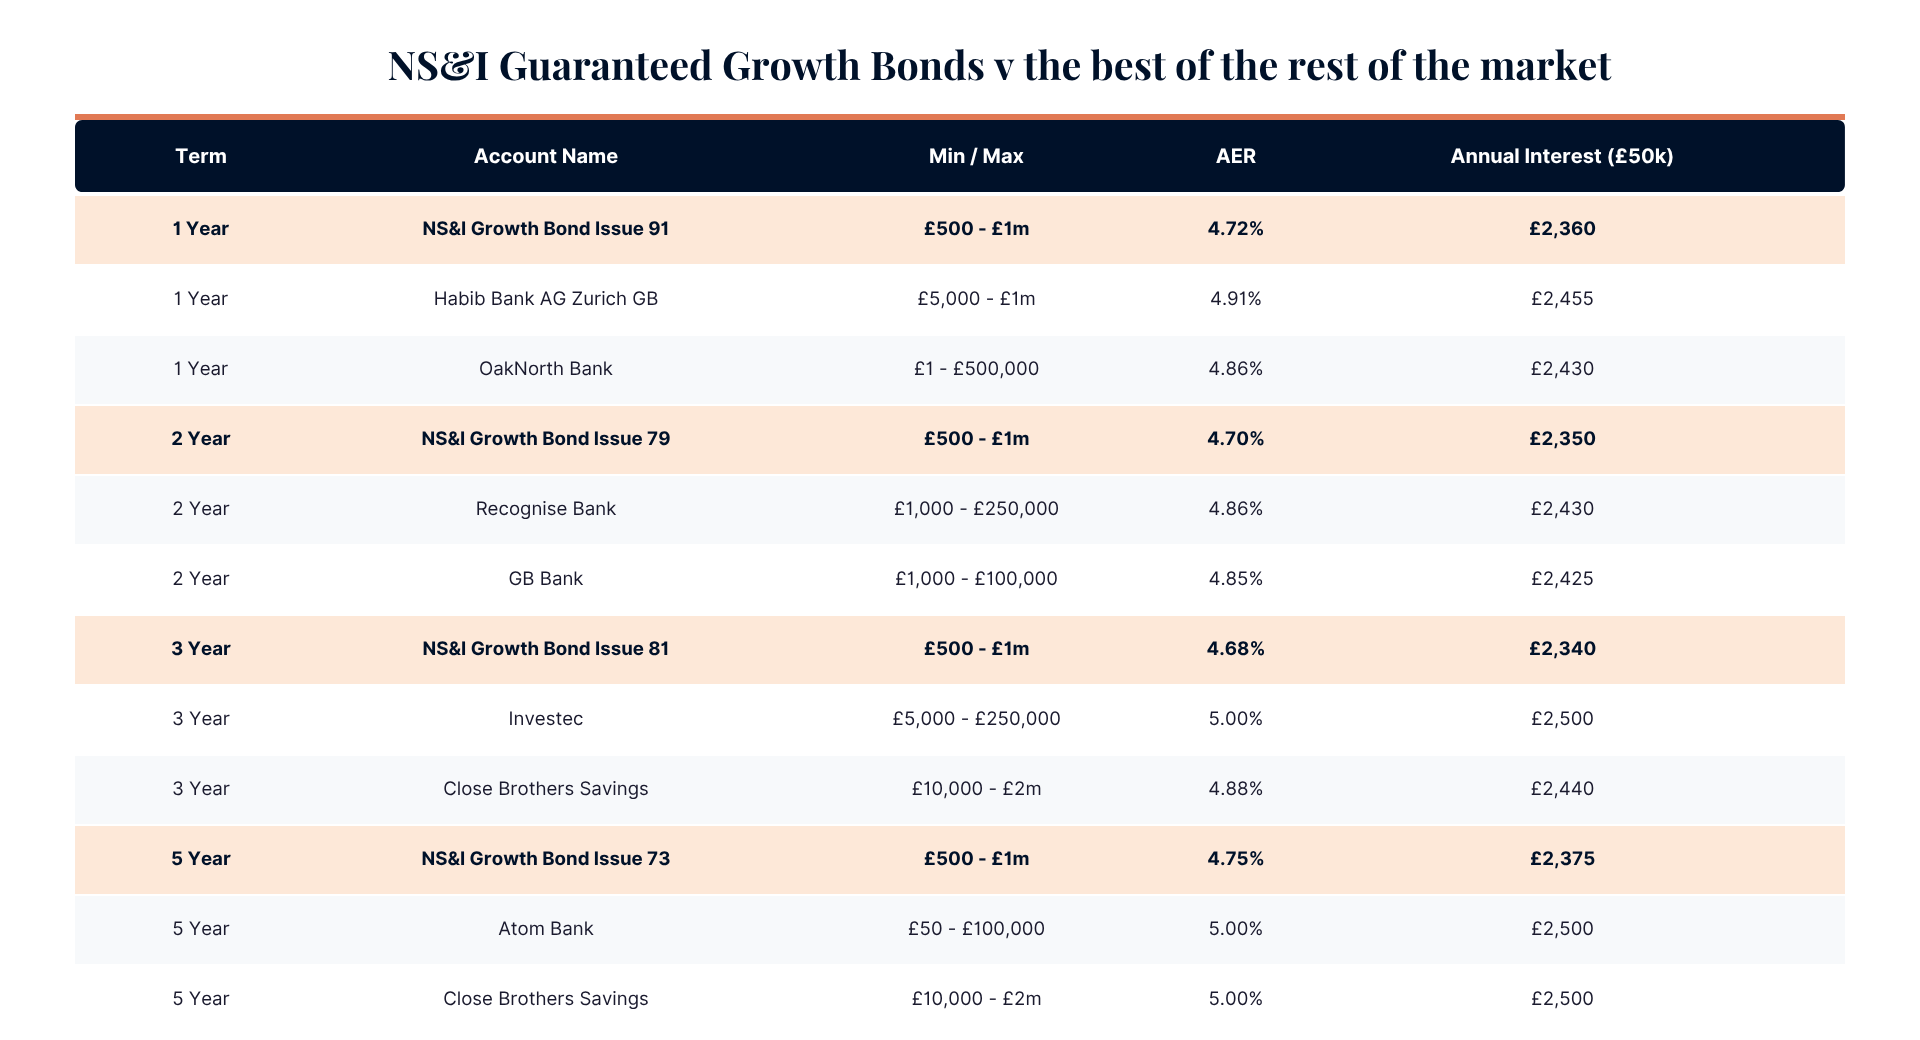
| Product | Previous interest rate (from 23rd June 2026) | New interest rate (from 31st July 2026) |
|---|---|---|
| Guaranteed Growth Bonds 1-year (Issue 91) | 4.69% gross/AER | 4.72% gross/AER |
| Guaranteed Income Bonds 1-year (issue 91) | 4.60% gross/ 4.69% AER | 4.63% gross/ 4.72% AER |
| Guaranteed Growth Bonds 2-year (issue 79) | 4.67% gross | 4.70% gross/ AER |
| Guaranteed Income Bonds 2-year (issue 79) | 4.58% gross/ 4.67%AER | 4.61% gross/ 4.70% AER |
| Guaranteed Growth Bonds 3-year (issue 81) | 4.65% gross/ AER | 4.68% gross/ AER |
| Guaranteed Income Bonds 3-year (issue 81) | 4.56% gross/ 4.65% AER | 4.59% gross/ 4.68% AER |
| Guaranteed Growth Bonds 5-year (issue 73) | 4.55% gross/ AER | 4.75% gross AER |
| Guaranteed Growth Bonds 5-year (issue 73) | 4.46% gross/ 4.55% AER | 4.65% gross/ 4.75% AER |
Why is NS&I increasing rates again?
Unlike commercial banks, NS&I has a very different objective.
Its role is to raise money for the Government in a cost-effective way, so rather than trying to get to the top of the best buy tables, it adjusts its interest rates to attract just enough money to meet its Net Financing Target; the amount NS&I needs to raise as a Government department, after allowing for withdrawals.
If too much money is flowing in, it can reduce rates. If it needs to attract more deposits, it can increase them.
Whilst the Net Financing raised for 2025/26 was £12.1 billion, so was within the leeway target for the year of plus or minus £4 billion, it was just under £1 billion less than the actual Net Financing Target of £13 billion. So perhaps NS&I realises that it needs to be more competitive to raise the funds needed, to meet the current tax years target especially given that the target is higher at £15 billion (+/- £4 billion).
Competition for savers' money has been strong this year. Fixed term bond rates have been climbing higher as banks and building societies compete for deposits, and NS&I will need to stay competitive if it wants to raise the funds it needs.
Competitive, but not market leading
NS&I has become more competitive, but it still is not offering the highest rates available.
Of course, if it did consistently top the best buy tables, it would almost certainly attract more money than it needs, making it more expensive for the Government to borrow through NS&I than necessary.
Instead, it aims to offer rates that are attractive enough to meet its funding target without distorting the wider savings market.
The latest increases narrow the gap and make the British Savings Bonds look much more appealing, particularly when compared with many of the accounts offered by the well-known High Street banks.
However, if savers are prepared to shop around and use a provider that they are perhaps less familiar with, they can still earn higher rates elsewhere. As long as that bank or building society is part of the Financial Services Compensation Scheme (FSCS), there is no reason not to take a well-informed leap of faith in order to earn more.
Why do many savers still choose NS&I
Of course, the interest rates are only part of the story. Security is another.
Money held with banks and building societies is protected by the Financial Services Compensation Scheme (FSCS), up to £120,000 per banking licence. Whilst that level of protection is more than enough for most people, those with larger cash balances often have to spread their money across several providers to remain fully protected.
One of the biggest attractions of NS&I is the security it offers. Every penny deposited is backed by HM Treasury, giving savers an unlimited Government guarantee.
For those who don’t have the time or inclination to open multiple savings accounts, this is one of the key reasons NS&I remains so popular, even when it is not paying the very highest rates.
Should you choose NS&I?
British Savings Bonds now compare more favourably when compared to many of the products offered by the High Street banks. And they remain one of the simplest ways for those with larger cash balances to benefit from the unique HMRC protection.
But that does not necessarily mean they are the best option.
If your main objective is to maximise the interest on your savings, then the bottom line is that you can earn far more by shopping around.
For the latest rates, visit our Best Buy tables.
Arrange your free initial consultation
Rates correct 04/08/2026
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
Is £50k a good salary in the UK?
Earning £50,000 a year should feel comfortable. For many people in 2026, it doesn't.
On paper, it's a good income and comfortably above the UK median full-time salary of £39,039. Yet many people earning £50,000 still find themselves wondering where their money goes each month.
Higher living costs, rising rents, mortgage affordability pressures and frozen tax thresholds mean that the gap between what £50,000 looks like on paper and what it feels like in your bank account can be significant.
Arrange your free initial consultation
Tax breakdown for earnings of £50,000
If you earn £50,000 as an employee in the UK in the 2026/27 tax year, your take-home pay will be roughly £39,519, which works out at about £3,293 a month.
This assumes you receive the standard Personal Allowance of £12,570. The remaining £37,430 is taxed at the basic rate of 20 per cent, giving an income tax bill of around £7,486. A £50,000 salary sits just below the higher rate threshold, which starts at £50,271.
You would also pay employee National Insurance. For 2026 to 2027 tax year, this is usually charged at 8 per cent on earnings between the Primary Threshold of £12,570 and the Upper Earnings Limit of £50,270. On a £50,000 salary, that means National Insurance of around £2,995.
Put together, income tax and employee National Insurance come to around £10,481. That is why a £50,000 salary does not translate into £4,167 a month in your pocket. Your final take-home pay may also vary depending on pension contributions, salary sacrifice, bonuses, taxable benefits, student loan deductions, other income, and whether you are a Scottish taxpayer, as Scotland uses different income tax bands.
You can find all the different tax allowances and reliefs in 2026-27 here
Living costs in the UK
The most recent Office for National Statistics (ONS) family spending figures show average weekly household expenditure of £623.30 in the financial year ending 2024, and this is estimated to have increased in the years since, due to the cost-of-living crisis.
Housing
Housing is often the single biggest factor.
If your rent is around the UK average, you may be spending close to 40 per cent of your take home pay on rent alone. The ONS reported that average UK monthly private rents reached £1,366 in November 2025, with higher averages in England and much higher costs in parts of London and the South East.
For solo renters, this can absorb a large part of your net income.
Imagine two people, both earning £50,000. One rents a one-bedroom flat in central London for £2,000 a month. The other owns a home in Yorkshire with a £900 monthly mortgage. It’s the same salary, and yet they have completely different living costs.
Now factor in childcare costs, student loan repayments, car finance, commuting expenses or re-mortgaging onto a higher interest rate, and the gap widens even further. It's why one person earning £50,000 has enough disposable income to save, while another reaches payday wondering where their salary has gone.
When it comes to buying a house, the average UK house price was £270,000 in December 2025, according to the latest UK House Price Index.
A common mortgage income multiple of around 4.5 times salary would suggest borrowing capacity of about £225,000, although lenders assess affordability more closely than this and will consider debts, dependents, credit history and regular spending. With a meaningful deposit, buying may be achievable in many areas, but it can still be difficult in more expensive regions.
Utilities and council tax
These are the types of essential costs that are difficult to reduce, which is why many people feel pressure on their disposable income even when earning above the national average.
Energy costs remain a meaningful monthly expense. Ofgem set the price cap for a typical household paying by Direct Debit at £1,641 a year from April to June 2026, although your actual bill will depend on usage, property type and tariff.
Council tax also matters. The average Band D council tax bill in England for 2026 to 2027 is £2,392. That is close to £199 a month before any discounts.
Transportation
Transport costs depend heavily on where you live. A commuter using rail into a major city may have far higher costs than someone working from home. If you run a car, then insurance, fuel, servicing, parking and finance payments can quickly eat into the disposable income that looks healthy on paper.
Groceries and dining out
Groceries are another area where inflation has changed the feel of a £50,000 salary. A weekly food shop, occasional meals out and small everyday purchases can now make a noticeable dent in monthly cash flow. Individually these purchases rarely seem significant, but together they can make a noticeable difference to how much is left at the end of the month
Leisure and entertainment
A £50,000 salary should still allow room for holidays, hobbies and socialising, but usually with some trade-offs. If you are also saving for a house deposit, contributing meaningfully to a pension or supporting family, leisure spending may need to be planned rather than casual.
Financial considerations and saving potential
A £50,000 income can be a strong foundation for building long-term wealth, but only if it's supported by a clear financial plan.
Savings
At this income level, you should ideally be building an emergency fund, keeping cash for known short term costs and using tax efficient allowances where appropriate.
Cash ISAs can be useful for savings you want to keep accessible while sheltering interest from tax, and Stocks and Shares ISAs may be suitable for longer term investing. You should also be aware of the Personal Savings Allowance, as interest on cash savings may become taxable once it exceeds your allowance.
If you already have at least £100,000 in investable assets, the question becomes less about whether you can save and more about how efficiently your money is working.
Pension contributions
Pension contributions are one of the most useful planning tools on a £50,000 salary. Your income is close to the higher rate tax threshold, so even modest pay rises, or a bonus could push some of your earnings into higher rate tax. Increasing pension contributions can help keep your taxable income below that threshold while building long term wealth, though it's important to note that you won't be able to access this money until retirement. This is currently age 55, but is increasing to 57 from April 2028.
Salary sacrifice can be especially helpful where available, as it may reduce both income tax exposure and National Insurance, depending on your employer’s scheme. Even relatively small increases in pension contributions made consistently over many years can have a significant impact on retirement outcomes thanks to investment growth and tax relief.
Debt management
Debt can change the whole picture. A £50,000 salary with no unsecured debt and manageable housing costs can feel comfortable. The same salary with credit card balances, car finance and high mortgage or rental costs can feel tight.
The priority is to understand which debts are expensive, which are strategic and which are restricting your ability to invest for the future.
Financial planning
This is often the point where financial advice starts to add real value. Around this level of income, many people find themselves balancing competing priorities. Should you overpay your mortgage or invest instead? Increase pension contributions or build your emergency fund? Make use of your ISA allowance or keep more cash available? There is rarely a single 'right' answer, but getting these decisions right can make a meaningful difference over the long term.
Is a pay rise above £50,000 worth it?
The short answer is yes. A common misconception is that moving into the higher-rate tax band leaves you worse off overall. In reality, only the income above the threshold is taxed at the higher rate, so you'll always take home more money after a pay rise.
Once your income moves above £50,270 in England, Wales and Northern Ireland, earnings above that threshold are generally taxed at 40 per cent, with employee National Insurance at 2 per cent above the Upper Earnings Limit. You’ll also lose 50% of your personal savings allowance, dropping from £1,000 a year tax free, to £500 a year, as soon as you fall into the higher rate tax bracket.
That does not mean you are worse off. It simply means each extra pound above the threshold may be taxed more heavily. Pension contributions can help manage this, particularly if you do not need all of the additional income immediately.
Career progression and future earnings
Though £50,000 is a reasonably high salary, the bigger question is whether your income is likely to rise, whether your career is resilient, and whether your savings and investments are growing alongside your earnings.
Frozen thresholds have changed the way many professionals experience pay rises. The Personal Allowance and higher rate threshold have been fixed since 2021/2022 tax year and are due to remain frozen until 2031, which means more people are being pulled into higher tax bands as pay increases.
So, is £50,000 a good salary?
By UK standards, yes. It remains comfortably above average and has the potential to support a good lifestyle, meaningful savings and long-term wealth. However, salary alone no longer guarantees financial comfort. How far your income goes depends on where you live, the financial commitments you have and, perhaps most importantly, the decisions you make with your money.
That's where financial planning can make a real difference. At TPO, we use Cash Flow Forecasting to help clients understand how today's financial decisions could shape their future, giving them greater confidence to enjoy their money now while still working towards long-term goals.
If you’d like help mapping out your financial future, why not get in touch for a free initial conversation to see how we can help.
Arrange your free initial consultation
This article is for information only and does not constitute individual advice. The information provided in this article is based on the current allowances and legislation and is subject to change.
The Financial Conduct Authority (FCA) does not regulate cash flow planning or tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available.