Skip to main content
Back to the future for pensions
After 40 years in the industry, I will be hanging up my boots at the end of the year and taking up a new career on the golf course.
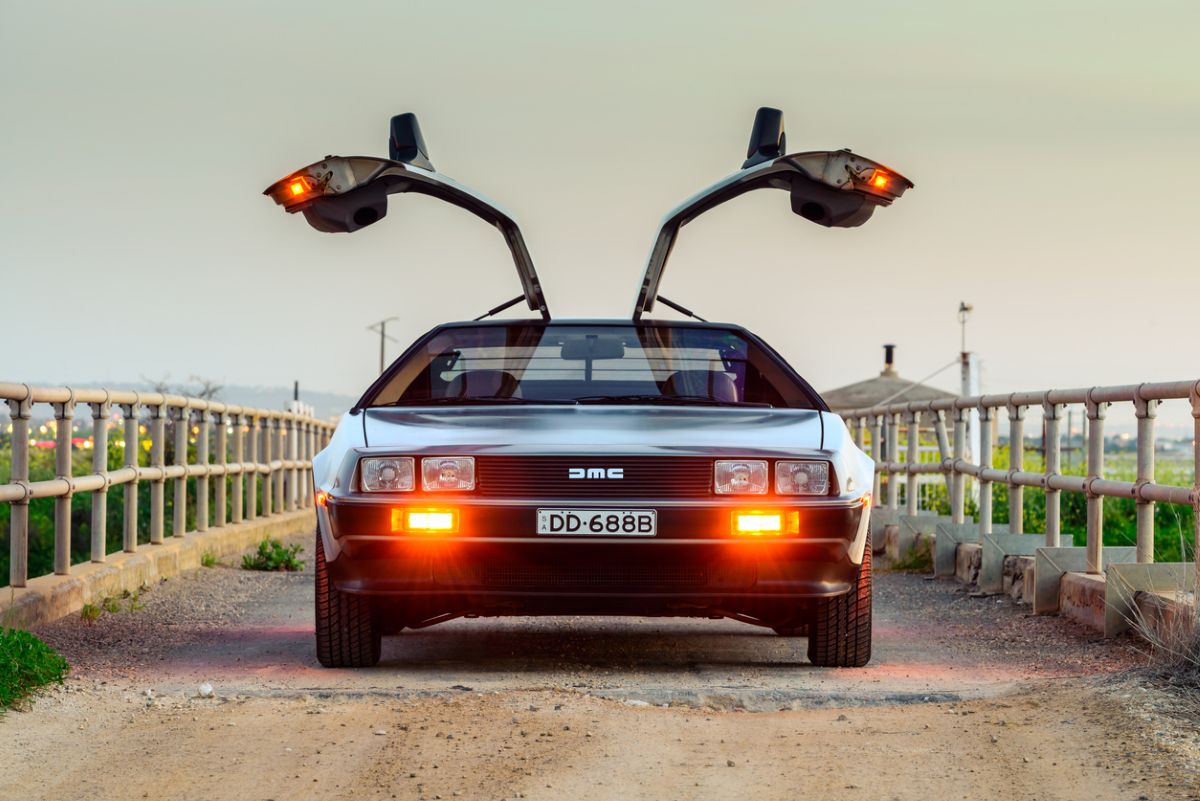
To say that I’ve seen a few changes in that time is an understatement but now, at the end of my career, I’ll take one last spin in the De Lorien and look at the twists and turns that pensions legislation has taken over the last four decades and how that has affected my clients.
Arrange your free initial consultation
The first thing I’d like to say is to offer my sympathies to the general public who have been subjected to rules and complexities which should really be the preserve of rocket science. The opaqueness of pensions has been a disservice to the consumer and for many, this lack of clarity has resulted in rejection. I really don’t blame anyone for this. I have a similar reaction if, for instance, I’m trying to work out which mobile phone package is best. In the end, there is a tendency to turn your back on the whole subject for fear of doing the wrong thing.
But let me make one thing clear. Pensions are, and always have been, the most tax efficient means of saving for retirement.
Stepping back to 1987
If I set my clock to 1987 and step out of my time machine, apart from the padded shoulders, I’m struck by the fact that full tax relief is available on contributions (up to a limit). This is still the case now and if I can say what the most common question clients ask just before a budget it’s “Do you think they will take away higher rate tax relief on pensions?”. Here I am, nearly 40 years later and this highly attractive property of pensions remains intact, yet I expect one last wave of this question before this, my final budget as an advisor.
Tax relief was even more attractive back then because income tax was higher. Who would turn their nose up at the opportunity to invest £40 and for it to be immediately worth £100 (the higher rate of income tax was 60% in 1987)? Many did though. Maybe they thought it was too good to be true. But it was!
In those days, personal pensions were mostly found amongst the self-employed as employed people often enjoyed final salary pension schemes. Over the years, final salary schemes have been culled from the private sector (they’re simply too expensive for employers to run). Now, unless you’re in the public sector, final salary pension schemes are like hens’ teeth.
What happened to pensions from 1995
Let’s get back in the De Lorien and get out in 1995. Until then personal pensions were restricted in that you had to buy an annuity when you retired. This was all very well and meant people didn’t have to worry about investment returns. Annuity rates were also high (although this really only reflected the fact that we had double digit inflation). By 1995, however, rates were reducing and there was growing unrest driven by the prospect of parting with your pension pot in exchange for a low annuity return. So, under John Major’s government, income drawdown was introduced and for the first time pension holders were allowed to keep their funds invested and take an income (within upper and lower limits). As gilt rates (and annuity rates) continued to tumble, we never looked back and drawdown was here to stay (albeit with some horror stories around high-risk portfolios suffering in subsequent market crashes).
Things bumbled along fairly uneventfully for the next twenty years but, in all this time, pensions were never attractive from an estate planning point of view, and nobody ever thought of them in this way. There were all sorts of complex rules which I have no intention of repeating here but, in essence, if pensions were left to anyone other than a spouse there was punitive tax. It was only when George Osborne announced pensions freedom in 2015 that the idea of pensions ‘cascading’ down the generations was invented. Before George, pension funds attracted a fairly hefty tax on death of 55%. Earlier than that and it could have been more, up to 82% in some circumstances. All of a sudden, there was no tax at all and pension funds, particularly for the very wealthy, were now parked for future generations. Furthermore, you could take the whole fund as drawdown. There was a lot of talk about Lambourghinis but, in truth, no one really wanted to draw out so much that they were subject to higher rate income tax.
Then came the Budget in 2024
Which brings us to the present and in 2024 Rachel Reeves announced that pensions would be subject to Inheritance Tax from 2027. Let’s put this into perspective and compare the taxation of a personal pension from 2014 to a pension in 2027. Let’s say leave it to your children as pensions passing to spouses is exempt from IHT. In 2014 it would have been subject to a 55% tax (if in drawdown) so they would end up with 45% of the fund. In 2027 there will be IHT, say 40% if the rest of the estate is substantial enough to use up the Nil Rate Band. This means that 60% is inherited but this, in turn, could be subject to income tax if they die after the age of 75. Let’s say the children are basic rate taxpayers. This means they will inherit, after tax, 48% of the fund compared to 45% in 2014.
There are, of course, situations where it is more punitive now (particularly if the children are higher rate) but the point is that in 2027 most people will be in a similar situation to tax legislation of 2014.
Will the government take away tax-free cash on pensions?
I think the second most common question I’ve had over the forty years is “Will they take away the tax free cash?”. True, it has been capped to the distinctly catchy number of £268,275 but, for most, it still stands at 25% of the fund. Will it be reduced further? Alas, I cannot go into the future, only the past. If I could have, I wouldn’t be here, would I? So, your guess is as good as mine.
In the final analysis, I would say that pensions are more attractive now than they were forty years ago. They are more flexible. Pensions are still inheritable, albeit distinctly less attractive from 2027. They are also cheaper to run. In the 80s most pensions were only available from insurance companies and charges were punitive. These days, plans are cleaner and don’t have initial charges. There is also much more choice of investment, not just a few vanilla funds. Drawdown is definitely a huge advantage, removing the compulsion to buy annuities. I should mention that you still can buy annuities and people still do, in certain circumstances. You could even have both annuity and drawdown.
But with more flexibility comes more responsibility. Good advice is absolutely essential, particularly when in drawdown. The greatest danger to any fund, from which meaningful withdrawals are being made, is something called Sequence Risk. This is the damaging effect on a portfolio if it is all invested in risk funds, and withdrawals are taken at the bottom of the market. A good adviser will recommend holding different risks for different timescales to negate this risk.
So, it’s time for me to forget about the past and buckle into the De Lorien to see what the future holds. I will now become a client of TPO and will see where the road takes us although, as Emmet Brown said “Where we’re going Marty, we don’t need roads”.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available. Your pension income could also be affected by the interest rates at the time you take your benefits.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.