Skip to main content
Are you prepared to die?
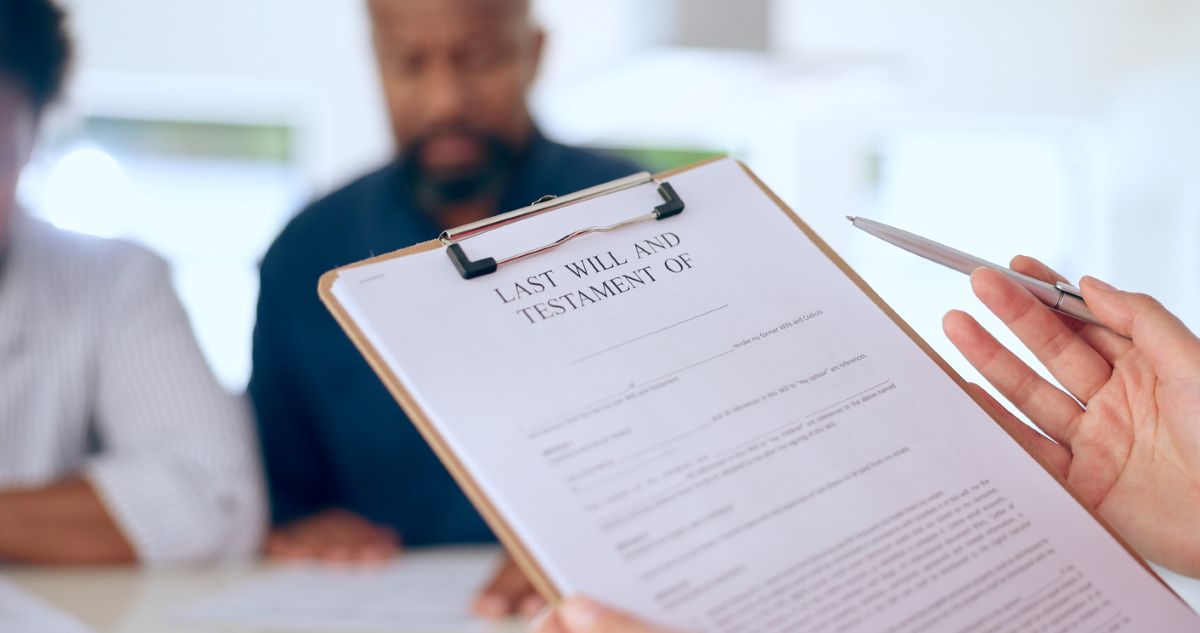
Passing away without adequate preparation carries a heavy price tag. Beyond the obvious costs of a memorial service or burial, families face substantial hidden financial and emotional burdens when they overlook proper estate planning. Key oversights such as omitting a valid Will, failing to register a Lasting Power of Attorney, leaving cohabiting partners without legal protection, or leaving financial gifts incomplete can inevitably increase the strain on grieving loved ones.
Research we recently conducted, alongside government and industry data, shows just how widespread this unpreparedness is in the UK – and how much it can cost, in time, money and stress, when families are left to work it out on their own.
Arrange your free initial consultation
How prepared are we, really?
On paper, most people know they should plan ahead. In practice, most haven't. A study by the Money and Pensions Service revealed that 56% of adults in the UK lack a will, with 53% of individuals aged 50–64 falling into this category – an age group where concerns about death and incapacity shift from distant thoughts to a closer possibility. This is also the period of time often referred to as “Sniper's Alley”, when people face a sharply increasing risk of serious health conditions. Without a will, the law decides who inherits, not the person who died – and the rules rarely match what people actually intended.
The preparedness gap extends to digital assets too. A survey by consumer group Which? found that 76% of people have left no plan for what happens to their digital assets when they die. This is especially concerning when finances are involved, with research from Finder, a financial comparison and consumer education platform, estimating that 50.1 million people in the UK now use some form of online or remote banking; that's 91% of the adult population. With many having a digital footprint spanning multiple logins, accounts and portals, often with no record of them held anywhere accessible, for families trying to settle an estate, tracking down that information can add weeks of stress on top of grief.
The gap is even wider when it comes to understanding legal protection within relationships. A Ministry of Justice consultation found that 47% of people in England and Wales believe "common law marriage" exists and gives legal protection after a set number of years together. It doesn’t and never has. With 3.5 million people now cohabiting outside marriage or a civil partnership, and fewer than half of UK adults married or in a civil partnership, that misconception leaves millions exposed. Under current intestacy rules, an unmarried partner has no automatic right to inherit anything from their partner's estate, regardless of how long they lived together or how finances were shared - a protection that at least the children can receive.
Without a will, even a decades-long partnership offers no legal protection. It is one of the starkest examples of what being unprepared can cost the people you leave behind. Even if a will does leave everything to an unmarried partner, there is no Inheritance Tax (IHT) spousal exemption, so IHT would need to be paid, unlike when assets are left to a spouse or civil partner, when there is no IHT payable.
The Private Office's (TPO) own survey of 2,126 UK adults*, mostly aged 45 and over, found that gifting early is desirable. The overwhelming majority, 80.7%, believe wealth should be passed on to the next generation during their lifetime rather than left to inheritance – 67.9% see helping with a first home as the moment support matters most.
Yet many hold back. Retirement security and long-term care costs together account for over half of the concerns people give when asked what stops them from gifting more or gifting at all, demonstrating that financial uncertainty in later life remains the biggest barrier to gifting. It is a solvable problem, however; those who plan early and build a clear picture of their future financial needs are far better placed to gift with confidence, knowing what they can afford to give without compromising their own security and hopefully leaving less tax for their loved ones to pay on their death.
| Top barriers to early gifting | % |
|---|---|
| Running out of money later in retirement | 37.3% |
| Care home costs | 15.5% |
| No concerns | 15.0% |
| Money won’t be used responsibly | 11.5% |
| Inheritance tax concerns | 10.7% |
| Economic uncertainty | 4.7% |
| Family disputes | 2.3% |
What being unprepared actually costs
Delay becomes deputyship. Without a registered Lasting Power of Attorney, a family that needs to manage a loved one's finances or care decisions after they lose mental capacity has to apply to the Court of Protection instead. Registering an LPA in good time costs £92; applying for deputyship after capacity is lost costs £400 – before factoring in the months it can take to get a court order in place, during which bills, care fees and property costs still need to be paid. Over a million LPAs were registered with the Office of the Public Guardian in 2023–24, a rise of more than 30% since 2019–20, showing more people are waking up to this – but the majority still haven't.
No will means no control, and often, no speed
When someone dies without a valid will, their estate is distributed under intestacy rules, which take no account of unmarried partners, stepchildren, or personal wishes. It also tends to take longer: according to DNA Legal, the number of probate cases taking over a year to resolve has risen 518% in five years, from 377 in 2019 to 2,328 in 2024, as estates become more complex and more contested.
Being unmarried carries a real financial cost
This is an increasingly significant issue given the growth in cohabiting families, which now number around 3.5 million in 2025, more than double the figure 30 years ago. For cohabiting couples, the absence of a will could mean losing a home they've lived in for decades if it isn't owned on a joint tenancy basis. A recent government consultation, which closed on 14 August 2026, examined whether unmarried partners should gain automatic inheritance rights if their partner dies without a will – a sign of how significant a gap this has become, but a change that, if it happens at all, is still some way off. For now, the only real protection is a will, and ideally a cohabitation agreement, drawn up in advance.
Gifting that stalls costs the giver peace of mind and the recipient certainty
TPO’s survey found that among people who haven't yet gifted, 39.7% still intend to – but uncertainty about their own future costs, particularly care, is often what stops a gift from being made or completed, while it would still help most. A gift promised but never followed through leaves both generations in limbo: the older generation still carrying the asset (and the tax exposure) they meant to pass on, and the younger generation still without the support they thought they could expect.
Practical steps: what "prepared" actually looks like
None of this requires anything dramatic – just a small number of documents and decisions, made once and reviewed regularly.
- Make a will and review it after any major life event – moving house, starting a new relationship, the arrival of a child, or the death of someone close. This is the biggest single gap in UK planning and the easiest to plug. Free Wills Month is a UK campaign run twice a year, in March and October, giving people aged 55+ the chance to have a simple will written or updated by a solicitor free of charge.
- Register a Lasting Power of Attorney for both property and financial affairs and health and welfare while you have full capacity to do so. It's a fraction of the cost and the stress of a deputyship application made in a crisis.
- If you're cohabiting, don't rely on "common law marriage." A will that names your partner, and a cohabitation agreement setting out how shared assets are treated, are currently the only reliable protections.
- If you're planning to gift, plan the whole gift, not just the giving. Whether it's help with a deposit, a contribution to a pension, or money into a Junior ISA or trust for a grandchild, working out what you can afford to give, and keeping that separate from what you might need for your own care, turns a gift into a plan rather than a decision made under pressure. Don’t forget that if you can make use of the 7 year rule and/or gift money out of surplus income, this can reduce the IHT liability to your loved ones.
- Create a digital death file. A will and an LPA tell people what to do, but they still need to be able to find the accounts, documents and contacts to act on those wishes. A secure digital file, one that stores your will, any trust details, tax information, professional contacts and emergency details, and that trusted people know how to access, removes a significant burden from the people left behind. You can also name a digital executor in your will to give someone specific responsibility for managing online accounts and digital assets. Without one, families can be left chasing logins and account details at exactly the moment they are least equipped to do so. At The Private Office, all clients have access to TPO Wealth, a secure online portal that acts as a digital filing cabinet for exactly this purpose, at no additional cost.
- Talk to your family about what you've decided, not just to a solicitor. Most of the stress in these situations comes from people finding out too late, not from the decisions themselves.
- Be aware of changes we know are coming. From April 2027, unused pension funds will form part of your estate for inheritance tax purposes, which is precisely why being prepared matters. Not only is this likely to bring more people into the IHT trap - and subject some beneficiaries to income tax as well as IHT - but it will also increase the burden on executors, who will need to account for all pensions held at the time of death. Having your affairs in order, with clear records of every pension you hold, is no longer just good practice; it is something your loved ones will be grateful for. It’s also essential to review who you have nominated your pension to on your death, as the new rules could mean that you might want to change your mind.
Having Peace of Mind
The more assets a family has, the more moving parts there tend to be – pensions, property, trusts, gifting plans – and the more those decisions need to work together rather than being made one at a time.
Talking about what happens when we die is never easy, and it’s understandable that people put it off. But from our experience, the biggest cost of not having these conversations is not only the financial cost, but the additional stress and uncertainty placed on the people we leave behind.
When a family is already dealing with the loss of someone they love, having to untangle their financial affairs or discover that arrangements weren’t quite what they thought, can make an incredibly difficult time even harder.
The good news is that getting your affairs in order doesn’t have to be complicated. A valid will, appropriate powers of attorney, clear records of your finances and some thought about how and when you want to pass on your wealth can make a significant difference.
It’s also important to look at these things as part of one overall plan, rather than as isolated decisions. Taking a little time now to understand what you have, what you want to happen and what your family might need means you can make those decisions on your own terms, rather than leaving them to others at a much more difficult time.
If you're not sure where your own plans stand, or it's been a while since you looked at them, talk to one of our advisers about reviewing them.
*The findings are drawn from a survey of 2,126 The Private Office newsletter subscribers, conducted in May 2026. The sample is weighted heavily towards older, asset-rich homeowners, reflecting the demographic most likely to be engaged in intergenerational wealth transfer. Respondents skewed towards the 65 and over age group (77% of the sample), with 40.1% aged 65 to 74 and 36.9% aged 75 and over. The remaining respondents were aged 55 to 64 (18.2%), 45 to 54 (3.8%) and under 45 (1.0%). In terms of housing status, 91.3% were outright homeowners, 5.5% held a mortgage, 1.4% rented privately, and 1.8% fell into other categories. 75.3% of respondents had children, grandchildren, or both.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.