Skip to main content
Are you prepared to die?
Passing away without adequate preparation carries a heavy price tag. Beyond the obvious costs of a memorial service or burial, families face substantial hidden financial and emotional burdens when they overlook proper estate planning. Key oversights such as omitting a valid Will, failing to register a Lasting Power of Attorney, leaving cohabiting partners without legal protection, or leaving financial gifts incomplete can inevitably increase the strain on grieving loved ones.
Research we recently conducted, alongside government and industry data, shows just how widespread this unpreparedness is in the UK – and how much it can cost, in time, money and stress, when families are left to work it out on their own.
Arrange your free initial consultation
How prepared are we, really?
On paper, most people know they should plan ahead. In practice, most haven't. A study by the Money and Pensions Service revealed that 56% of adults in the UK lack a will, with 53% of individuals aged 50–64 falling into this category – an age group where concerns about death and incapacity shift from distant thoughts to a closer possibility. This is also the period of time often referred to as “Sniper's Alley”, when people face a sharply increasing risk of serious health conditions. Without a will, the law decides who inherits, not the person who died – and the rules rarely match what people actually intended.
The preparedness gap extends to digital assets too. A survey by consumer group Which? found that 76% of people have left no plan for what happens to their digital assets when they die. This is especially concerning when finances are involved, with research from Finder, a financial comparison and consumer education platform, estimating that 50.1 million people in the UK now use some form of online or remote banking; that's 91% of the adult population. With many having a digital footprint spanning multiple logins, accounts and portals, often with no record of them held anywhere accessible, for families trying to settle an estate, tracking down that information can add weeks of stress on top of grief.
The gap is even wider when it comes to understanding legal protection within relationships. A Ministry of Justice consultation found that 47% of people in England and Wales believe "common law marriage" exists and gives legal protection after a set number of years together. It doesn’t and never has. With 3.5 million people now cohabiting outside marriage or a civil partnership, and fewer than half of UK adults married or in a civil partnership, that misconception leaves millions exposed. Under current intestacy rules, an unmarried partner has no automatic right to inherit anything from their partner's estate, regardless of how long they lived together or how finances were shared - a protection that at least the children can receive.
Without a will, even a decades-long partnership offers no legal protection. It is one of the starkest examples of what being unprepared can cost the people you leave behind. Even if a will does leave everything to an unmarried partner, there is no Inheritance Tax (IHT) spousal exemption, so IHT would need to be paid, unlike when assets are left to a spouse or civil partner, when there is no IHT payable.
The Private Office's (TPO) own survey of 2,126 UK adults*, mostly aged 45 and over, found that gifting early is desirable. The overwhelming majority, 80.7%, believe wealth should be passed on to the next generation during their lifetime rather than left to inheritance – 67.9% see helping with a first home as the moment support matters most.
Yet many hold back. Retirement security and long-term care costs together account for over half of the concerns people give when asked what stops them from gifting more or gifting at all, demonstrating that financial uncertainty in later life remains the biggest barrier to gifting. It is a solvable problem, however; those who plan early and build a clear picture of their future financial needs are far better placed to gift with confidence, knowing what they can afford to give without compromising their own security and hopefully leaving less tax for their loved ones to pay on their death.
| Top barriers to early gifting | % |
|---|---|
| Running out of money later in retirement | 37.3% |
| Care home costs | 15.5% |
| No concerns | 15.0% |
| Money won’t be used responsibly | 11.5% |
| Inheritance tax concerns | 10.7% |
| Economic uncertainty | 4.7% |
| Family disputes | 2.3% |
What being unprepared actually costs
Delay becomes deputyship. Without a registered Lasting Power of Attorney, a family that needs to manage a loved one's finances or care decisions after they lose mental capacity has to apply to the Court of Protection instead. Registering an LPA in good time costs £92; applying for deputyship after capacity is lost costs £400 – before factoring in the months it can take to get a court order in place, during which bills, care fees and property costs still need to be paid. Over a million LPAs were registered with the Office of the Public Guardian in 2023–24, a rise of more than 30% since 2019–20, showing more people are waking up to this – but the majority still haven't.
No will means no control, and often, no speed
When someone dies without a valid will, their estate is distributed under intestacy rules, which take no account of unmarried partners, stepchildren, or personal wishes. It also tends to take longer: according to DNA Legal, the number of probate cases taking over a year to resolve has risen 518% in five years, from 377 in 2019 to 2,328 in 2024, as estates become more complex and more contested.
Being unmarried carries a real financial cost
This is an increasingly significant issue given the growth in cohabiting families, which now number around 3.5 million in 2025, more than double the figure 30 years ago. For cohabiting couples, the absence of a will could mean losing a home they've lived in for decades if it isn't owned on a joint tenancy basis. A recent government consultation, which closed on 14 August 2026, examined whether unmarried partners should gain automatic inheritance rights if their partner dies without a will – a sign of how significant a gap this has become, but a change that, if it happens at all, is still some way off. For now, the only real protection is a will, and ideally a cohabitation agreement, drawn up in advance.
Gifting that stalls costs the giver peace of mind and the recipient certainty
TPO’s survey found that among people who haven't yet gifted, 39.7% still intend to – but uncertainty about their own future costs, particularly care, is often what stops a gift from being made or completed, while it would still help most. A gift promised but never followed through leaves both generations in limbo: the older generation still carrying the asset (and the tax exposure) they meant to pass on, and the younger generation still without the support they thought they could expect.
Practical steps: what "prepared" actually looks like
None of this requires anything dramatic – just a small number of documents and decisions, made once and reviewed regularly.
- Make a will and review it after any major life event – moving house, starting a new relationship, the arrival of a child, or the death of someone close. This is the biggest single gap in UK planning and the easiest to plug. Free Wills Month is a UK campaign run twice a year, in March and October, giving people aged 55+ the chance to have a simple will written or updated by a solicitor free of charge.
- Register a Lasting Power of Attorney for both property and financial affairs and health and welfare while you have full capacity to do so. It's a fraction of the cost and the stress of a deputyship application made in a crisis.
- If you're cohabiting, don't rely on "common law marriage." A will that names your partner, and a cohabitation agreement setting out how shared assets are treated, are currently the only reliable protections.
- If you're planning to gift, plan the whole gift, not just the giving. Whether it's help with a deposit, a contribution to a pension, or money into a Junior ISA or trust for a grandchild, working out what you can afford to give, and keeping that separate from what you might need for your own care, turns a gift into a plan rather than a decision made under pressure. Don’t forget that if you can make use of the 7 year rule and/or gift money out of surplus income, this can reduce the IHT liability to your loved ones.
- Create a digital death file. A will and an LPA tell people what to do, but they still need to be able to find the accounts, documents and contacts to act on those wishes. A secure digital file, one that stores your will, any trust details, tax information, professional contacts and emergency details, and that trusted people know how to access, removes a significant burden from the people left behind. You can also name a digital executor in your will to give someone specific responsibility for managing online accounts and digital assets. Without one, families can be left chasing logins and account details at exactly the moment they are least equipped to do so. At The Private Office, all clients have access to TPO Wealth, a secure online portal that acts as a digital filing cabinet for exactly this purpose, at no additional cost.
- Talk to your family about what you've decided, not just to a solicitor. Most of the stress in these situations comes from people finding out too late, not from the decisions themselves.
- Be aware of changes we know are coming. From April 2027, unused pension funds will form part of your estate for inheritance tax purposes, which is precisely why being prepared matters. Not only is this likely to bring more people into the IHT trap - and subject some beneficiaries to income tax as well as IHT - but it will also increase the burden on executors, who will need to account for all pensions held at the time of death. Having your affairs in order, with clear records of every pension you hold, is no longer just good practice; it is something your loved ones will be grateful for. It’s also essential to review who you have nominated your pension to on your death, as the new rules could mean that you might want to change your mind.
Having Peace of Mind
The more assets a family has, the more moving parts there tend to be – pensions, property, trusts, gifting plans – and the more those decisions need to work together rather than being made one at a time.
Talking about what happens when we die is never easy, and it’s understandable that people put it off. But from our experience, the biggest cost of not having these conversations is not only the financial cost, but the additional stress and uncertainty placed on the people we leave behind.
When a family is already dealing with the loss of someone they love, having to untangle their financial affairs or discover that arrangements weren’t quite what they thought, can make an incredibly difficult time even harder.
The good news is that getting your affairs in order doesn’t have to be complicated. A valid will, appropriate powers of attorney, clear records of your finances and some thought about how and when you want to pass on your wealth can make a significant difference.
It’s also important to look at these things as part of one overall plan, rather than as isolated decisions. Taking a little time now to understand what you have, what you want to happen and what your family might need means you can make those decisions on your own terms, rather than leaving them to others at a much more difficult time.
If you're not sure where your own plans stand, or it's been a while since you looked at them, talk to one of our advisers about reviewing them.
*The findings are drawn from a survey of 2,126 The Private Office newsletter subscribers, conducted in May 2026. The sample is weighted heavily towards older, asset-rich homeowners, reflecting the demographic most likely to be engaged in intergenerational wealth transfer. Respondents skewed towards the 65 and over age group (77% of the sample), with 40.1% aged 65 to 74 and 36.9% aged 75 and over. The remaining respondents were aged 55 to 64 (18.2%), 45 to 54 (3.8%) and under 45 (1.0%). In terms of housing status, 91.3% were outright homeowners, 5.5% held a mortgage, 1.4% rented privately, and 1.8% fell into other categories. 75.3% of respondents had children, grandchildren, or both.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
State Pension to be taxed following rise
The full State Pension is due to rise to above £13,000 a year, raising fresh questions about the growing cost of the system and fairness between generations.
Under the ‘triple lock’, payments rise by whichever is highest of average wage growth, inflation or 2.5%.
The latest figures from the Office for National Statistics (ONS) showed total wage growth, including bonuses, stood at 3.9% in the quarter to July, down from 4.2% in the three months to June. These earnings figures would mean the full, flat rate State Pension would increase by 3.9% or £488 next April to £13,036.40.
However, this won’t be locked in until the inflation figures for September are published in October, as they could in theory be higher than the 3.9% taken from total wage growth. The inflation figures for August were released on Wednesday, showing that inflation had risen to 3.1% in the 12 months to August, up from 2.9% in July.
The State Pension age is rising to 67 in April 2028, but government spending continues to increase. The annual State Pension bill is expected to reach £154bn this year and could rise by a further £600m a year by 2029/30 according to estimates.
Economists have raised concerns about the cost of the State Pension ahead of the Budget, as with this raise, pensioners are beating headline inflation at a time when many are struggling to keep pace, while pensioner groups argue that many older people still face poverty. Additionally, with this increase, the State Pension will breach the personal allowance threshold, making it in theory liable to be taxed.
The ‘Triple Lock’ explained
The ‘triple lock’ refers to a well-known State Pensions policy introduced in 2010 by the Conservative and Liberal Democrat Coalition Government that ensures State Pensions rise every year by either the average earnings growth, inflation (as measured by the Consumer Prices Index) or a flat 2.5% - whichever is highest that year, hence the name ‘triple’ lock.
It was designed in principle to make sure that State Pension value would always have the best growth outcome each year for pensioners. The guarantee that the highest of the three variables will be what pensions grow by ensures that Pensioners have three layers of protection against inflation, hence the name ‘triple lock’. This is incredibly important in maintaining a level of healthy financial security for those relying on their pensions, as it guarantees growth irrespective of how volatile the economy becomes.
If you want to find out more about retirement planning, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered financial advisers to find out how we might be able to help you.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
Over a million pensioners pushed into higher rate tax
The number of pensioners paying higher rate tax has doubled in the past five years, according to a recent freedom of information (FOI) request from Sir Steve Webb, UK's former Minister of State for Pensions.
Now, over a million pensioners are paying higher rate tax or more this year, up from half a million in 2021-22, with the number of pensioners paying additional rate tax, a tax band originally intended for only the highest earners in society, having trebled during the same timeframe.
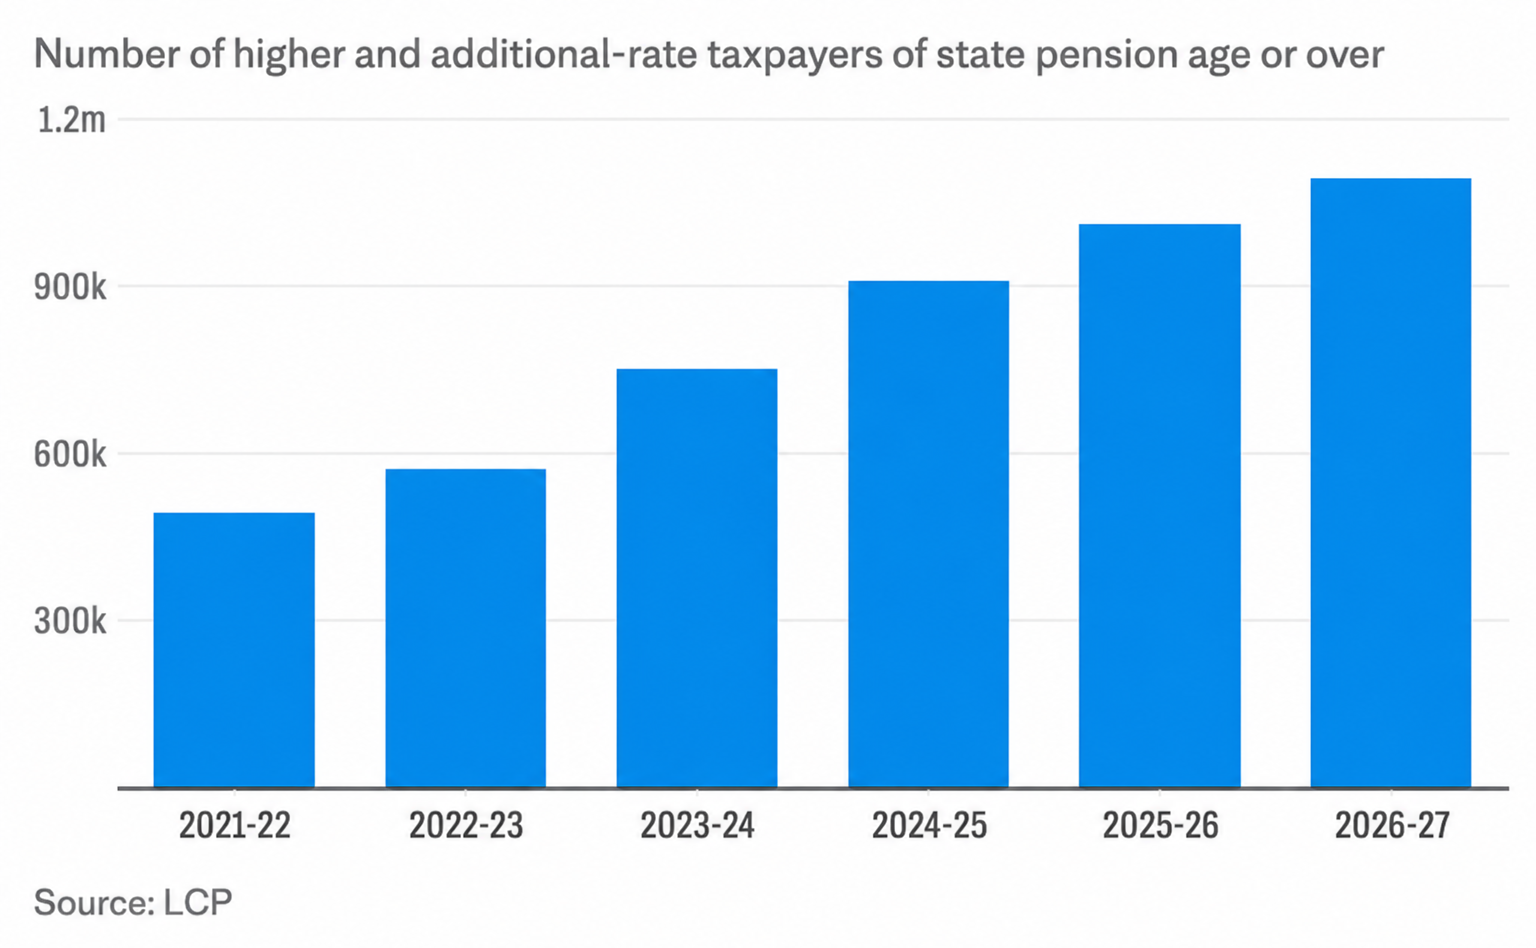
Once again, frozen thresholds or ‘stealth taxes’ are at the root of the issue, as the net widens, capturing more pensioners in the higher rate tax bands. According to the FOI data, the number of pensioners paying higher and additional rates of income tax has risen as state pension incomes increase in line with inflation while income tax thresholds remain frozen.
With thresholds set to stay at their current levels until April 2031, more retirees are likely to find that growing state and private pension income takes them into higher tax bands.
As this continues, it is likely to affect retirement planning for many workers. If a greater share of pension income is lost to tax, people may need to build up larger pension pots and savings during their working lives to achieve the level of income they want in retirement.
Arrange a free initial consultation
The forever frozen allowances
It has become the new norm for each Government to announce a further freeze on allowances, kicking the can down the road with each successive freeze, all the while taxpayers are being forced to hand over increasing amounts as fiscal drag pulls them ever further beyond the outdated thresholds.
One example of this is inheritance tax (IHT). Total IHT receipts collected by the Government has been steadily on the rise since the IHT threshold freeze.
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026. However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this move an example of ‘stealth tax’, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if indeed it does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the taxpayer.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered advisers to find out how can help.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available.
Your pension income could also be affected by the interest rates at the time you take your benefits. The tax implications of pension withdrawals will be based on your individual circumstances, tax legislation and regulation which are subject to change. You should seek advice to understand your options at retirement.
Families hit by inheritance tax on pensions
From next April, grieving families will not only be taxed on their loved one’s pensions, but will also be prevented from claiming loss reliefs on those pension pots under new planned taxation rules.
Under these plans, estates could face higher tax bills and extra late payment interest at the worst possible time while dealing with a bereavement.
Previously, pension pots were exempt from inheritance tax (IHT) and not included in the taxable estate after someone died, but following an announcement last year from former chancellor Rachel Reeves, pension pots will now be included in an individual’s estate from April 2027, meaning they will be subject to IHT on death like any other part of an estate.
Currently, if an asset is sold at a loss within 12 months of the death, family members are entitled to reclaim the difference in tax from HM Revenue & Customs (HMRC) through “loss on sale relief”. However, the same rule will not apply to pensions if they fall in value.
HMRC confirmed that certain IHT reliefs will not apply to unused pension assets as the deceased isn’t classed as owning the assets before death, despite being taxed like the rest of the estate. Executors will be unable to claim loss on sale relief, business property relief, agricultural property relief or pay inheritance tax by instalments on qualifying pension assets, despite those reliefs remaining available for assets held outside pensions.
There is concern that this could create a 'two-tier' system, where pensions will have less protections from tax.
What is inheritance tax?
Inheritance Tax (IHT) is a tax levied by the Government on the estate of a deceased person in the UK. This covers all of their assets including property, personal belongings, investments and, from April 2027, it also includes pensions.
However, this levy only applies to the total value of the estate that exceeds the IHT threshold or ‘nil-rate band’. As of the 2025/26 tax year, the threshold is set at £325,000. Anything above £325,000 could be subject to up to 40% inheritance tax and anything below this threshold is tax-free. In addition, an extra allowance known as the residence nil rate band (RNRB) of up to £175,000 may apply when a main home is passed to direct descendants, potentially increasing the total tax-free threshold to £500,000 for an individual.
Traditionally pensions have been exempt from inheritance tax but, from April 2027, pensions will no longer have this exempt status. This means that inheritance tax may have to be paid on your pension when you die.
If you’re interested in how to manage your inheritance tax to ensure the best possible wealth protection for you or your family, we can help. Give us a call on 0333 323 9065 or book a free non-committal initial consultation with a member of our team to find out more.
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available.
A million more workers hit by stealth taxes
A million more workers will have to pay income tax this year, according to research done by the new Taxpayers Alliance (TPA), with those aged over 65s getting hit the hardest.
According to the TPA report, in the 2026/27 tax year, a million more workers than the previous year are forecast to be paying income tax, following the continuing trend of more workers paying tax as personal allowance tax thresholds remain frozen, a type of taxation strategy known as ‘stealth tax’.
Arrange a free initial consultation
On average, taxpayers will pay £640 more in income tax in 2026/27 compared to 2024/25, and £1,040 more compared to 2023/24.
Over 65s are getting hit the hardest however, with the number of pensioners liable for income tax up by 630,000 in a single year, totalling 10.2 million pensioners now once again paying a portion of their income back to the Government.
Of these, 9.5 million are of state pension age, meaning seven in every ten pensioners are now taxpayers.
With many allowances remaining frozen, such as inheritance tax, the personal allowance, and income tax, coupled with an increasingly aging population that is living longer each decade, the resulting tax raid is less of a surprise and more of an economic inevitability.
New Prime Minister Andy Burnham initially hinted he would address the frozen threshold issues around the personal allowance. However, he has since pulled back on this issue. With the freeze expected to pull in £55 billion by 2030 for the Treasury’s coffers, and the expected £9 billion it would cost to uprate it in line with inflation, it is unlikely that any changes will be seriously discussed until the upcoming Autumn 2026 Budget.
To give you an idea of the amount of money you are effectively losing through this freezing strategy, the personal allowance currently sits at £12,570, where it has remained since April 2021. If the personal allowance had risen in line with inflation, it would now sit at £17,380.
The forever frozen allowances
It has become the new norm for each Government – regardless of the Party - to announce a further freeze on allowances, kicking the can down the road with each successive freeze. All the while taxpayers are being forced to hand over increasing amounts as fiscal drag pulls them ever further beyond the out-of-date thresholds.
One example of this is Inheritance tax (IHT). Total IHT receipts collected by the Government have been steadily on the rise since the IHT threshold freeze.
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026. However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this move an example of stealth tax, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if it indeed does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the taxpayer.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered advisers to find out how can help.
Arrange a free initial consultation
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
Living Inheritance: how grandparents are reshaping the transfer of wealth
Recent estimates from the Institute for Fiscal Studies suggest the annual value of financial gifts in the UK has now reached £17 billion, with around £9.6 billion going directly towards helping first-time buyers purchase a home. The growing reliance on family wealth highlights the increasing pressure younger generations face in saving for deposits independently, amid general ongoing affordability challenges.
These figures reflect a broader attitudinal shift. A recent survey of 2,126 UK adults aged 45 and over, found that 81% believe parents or grandparents should help younger generations financially during their lifetime rather than just leaving an inheritance on death. A further 83% say younger generations are more reliant on family support than previous ones.
Arrange a free initial consultation
While early inheritance can help children and grandchildren get onto the property ladder, clear debts, or build financial stability, it’s important for those making the gifts to make sure that they don’t fall foul of the gifting rules if they are also hoping to reduce a potential inheritance tax (IHT) liability, and to ensure that they don’t leave themselves financially exposed later in retirement.
Estates of those aged 85+ account for almost 60% of cases of lifetime gifts
According to a Freedom of Information (FOI) request made to His Majesty's Revenue and Customs (HMRC) in May 2026, data shows that in 2022/23 people aged 85 and over account for nearly 60% of all estates that included gifts, as well as the largest share of the total value gifted, suggesting that gifting is largely an end-of-life financial decision.
That said, feedback from our survey suggests this timing does not always reflect preference. We found that 71% of those surveyed say financial support should be given “early, when it can make the biggest impact”. Only 8% believe wealth should mainly be passed on after death, pointing to a growing gap between when people currently give and when they feel it would have a bigger impact.
The figures from the FOI request also show that only a minority of lifetime gifts end up being taxed through inheritance tax. In 2022–23, around 15% of estates that included gifts paid inheritance tax on them, suggesting most gifts fell within tax-free allowances or were otherwise exempt.
86% of those surveyed have already gifted or loaned money to family members
The vast majority of those surveyed have already acted on their views, with 82% having gifted outright, whilst 12% have loaned the money. The purpose of the support tells an interesting story. Property purchase comes at the top of the list, with 51% of those citing this reason. This is followed by general living support (20%) and educational costs (8%).
Among those who have not yet gifted (14%), 40% plan to do so. Of those, outright gifts before death remain the preferred form (59%), with inheritance via a will cited by nearly a third.
Family financial assistance remains a major factor in UK homeownership
Our survey underlines just how important helping loved ones onto the housing ladder has become. 97% of those surveyed say it is difficult or very difficult for young people to buy a home without family support, and 80% believe homeownership is becoming increasingly dependent on family wealth. Meanwhile, 88% say they would consider helping children or grandchildren to purchase a property, with property purchase already accounting for 51% of all support given by survey respondents, making it by far the most common use of family wealth.
External data supports this picture. Savills' 2025 property report found that 52% of first-time buyers in 2024 received family financial assistance, with the average contribution now reaching an eye watering £55,572.
The Bank of Mum & Dad provided £38.5 billion in support over the past four years, a 71% increase compared to the previous four-year period. Rising interest rates and more challenging mortgage conditions have made it increasingly difficult for younger buyers to purchase without help from family members.
The benefits and risks of early inheritance gifting
Our survey* confirms that the willingness to give sooner is high with 64% of those surveyed saying they would feel comfortable giving a large sum to younger family members during their lifetime. Yet retirement security remains a genuine brake on generosity. The biggest barrier to early gifting is the fear of running out of money in later life, cited by 37% of respondents, followed by concern about care home costs (16%). Together, these account for more than half of all concerns raised, reinforcing the importance of professional financial planning for anyone considering gifting in their lifetime.
What this research makes clear is that the 'Bank of Mum and Dad' has also become the Bank of Grandparents too. We're seeing a genuine generational shift in how people think about wealth — away from the traditional inheritance model and towards active, purposeful giving during their lifetime.
Early inheritance gifting can be a great way to provide financial support to loved ones at key life stages, but it must be balanced carefully against long-term income needs, tax considerations and estate planning objectives. With the right structure in place, families can pass on wealth in a way that is both efficient and aligned with their wider financial plans, reducing the risk of unintended tax consequences or future shortfalls in retirement income.
The question isn't always 'should I give?’, it's 'how much can I safely give?' That's exactly where good financial planning makes a real difference. With the right advice, families can transfer wealth in a way that supports the next generation without compromising their own retirement.
TPO Partner, David Dodgson, appeared on BBC Money Box Live on Saturday 25th July covering this subject (he's on from 16 minutes into the programme). He answered listener questions, explained the options and exemptions available to those looking to gift and shared his knowledge on gifting surplus income.
If you are considering gifting as part of your wider estate or retirement strategy, it is worth seeking tailored advice before making any decisions; if you make a mistake, it can be costly. HMRC collected an estimated £336 million in inheritance tax (IHT) over the past five years from failed gifting arrangements, after the assets involved were deemed not to have been fully given away.
*The findings are drawn from a survey of 2,126 The Private Office newsletter subscribers, conducted in May 2026. The sample is weighted heavily towards older, asset-rich homeowners, reflecting the demographic most likely to be engaged in intergenerational wealth transfer. Respondents skewed towards the 65 and over age group (77% of the sample), with 40.1% aged 65 to 74 and 36.9% aged 75 and over. The remaining respondents were aged 55 to 64 (18.2%), 45 to 54 (3.8%) and under 45 (1.0%). In terms of housing status, 91.3% were outright homeowners, 5.5% held a mortgage, 1.4% rented privately, and 1.8% fell into other categories. 75.3% of respondents had children, grandchildren, or both.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions. The Financial Conduct Authority (FCA) does not regulate tax advice.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
HMRC warns landlords about impending tax deadline
With the 31 July deadline closing in, HM Revenue and Customs (HMRC) is reminding millions of Self Assessment tax payers to complete their tax return before the deadline.
In particular, landlords and sole traders with an annual turnover above £50,000 are now required to use Making Tax Digital (MTD) for Income Tax, submitting quarterly updates to HMRC. The first quarterly submissions deadline for the 2026/27 tax year is 7 August 2026. More than 864,000 sole traders and landlords are expected to comply with the first phase of the MTD system.
Generally however, the deadline is for taxpayers who make ‘Payments on Account’ – advance payments towards their next Self Assessment tax bill, based on the amount of tax they owed the previous year. These are designed to spread the cost of a tax bill across two instalments rather than paid in one lump sum, which each payment worth half the previous year’s tax bill.
For most people, the first instalment was due on 31 January, while the second must be paid by midnight on Thursday, 31 July. Any outstanding balance remaining is then payable by the following 31 January.
HMRC lays out a number of ways to pay. All the usual methods such as bank transfer, direct debit and online banking apply, but you can also use the HMRC app.
Myrtle Lloyd, HMRC’s Chief Customer Officer, commented on the upcoming deadline:
“We know managing a Self Assessment tax bill isn’t always straightforward and we are here to help. From paying instantly via the HMRC app to spreading the cost through a payment plan, there’s support available for every customer.”
“Search ‘Pay your Self Assessment tax bill’ on GOV.UK to choose the payment option that works for you.”
What is ‘Self-Assessment’?
Self-Assessment is the process you go through each year where you complete a tax return and declare your income, capital gains and any other income during that tax year to HMRC, outside of income tax that is normally deducted from your wage or pension.
Millions of workers complete Self-Assessment each year, with 11.48 million received by the 31 January deadline earlier this year.
Although most commonly done by those who are self-employed, anyone who has other income outside what is normally deducted from your wages and pension, need to complete a self-assessment form – which can be paper based or digital.
Irrespective of employment status, if you have received any untaxed income before the deadline of that tax year, you may need to complete a tax return. Even if that income comes from Ebay, Etsy or similar enterprises.
For further information, check out our free guide on tax planning strategies. Alternatively, give us a call on 0333 323 9065 to book a free non-committal initial consultation with a member of our team.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax or trust advice.
NS&I makes more rate hikes
Bearing in mind that the Bank of England maintained the base rate at 3.75% at its latest Monetary Policy Committee (MPC) meeting on 18th June, it was interesting to see that National Savings & Investments (NS&I) subsequently announced rate increases to its fixed rate savings accounts, Guaranteed Growth Bonds and Guaranteed Income Bonds – also known as British Savings Bonds.
What are the new NS&I Guaranteed Growth Bond rates?
- 1-year bond: up from 4.50% to 4.69% AER
- 2-year bond: up from 4.48% to 4.67% AER
- 3-year bond: up from 4.45% to 4.65% AER
- 5-year bond: up from 4.40% to 4.55% AER
Whilst inflation has remained steady in the 12 months to May 2026 at 2.80%, we still expect inflation to jump up a little in the near future, as the effects of the war in the Middle East bite – and we know that the energy price cap increased by 13% this month!
However, the expectation that the base rate would remain the same this month is reflected by the slowdown in savings rate hikes that we’ve seen recently. So, it’s good news that NS&I is getting in on the action.
As well as reacting to the rest of the market, NS&I also adjusts rates it is offering, to manage the flow of funds into the state-owned Bank, to help it meet its Net Financing Target - the amount it is tasked with raising for the Government each tax year after taking account of both deposits and withdrawals.
The target has been increased from £13.6 billion to £15 billion for the 2026/27 tax year. In addition, the recent revelation that some bereaved families had not received all the money due from deceased relatives’ NS&I accounts, may have prompted higher than usual withdrawals. According to the Bank of England, some £160million was withdrawn in the first month of the tax year.*
Be aware if you choose the monthly income option
The British Savings Bonds offer a choice between having the interest paid monthly as income, or allowing it to roll up and be paid at maturity.
That choice is worth thinking about carefully, particularly if you pay tax on your savings.
If you choose to have the interest added to the bond each year so that it compounds, you won't receive it until the bond matures, which could be more important in longer term bonds. For tax purposes, that means all the interest is treated as being received in the tax year in which the bond ends.
Because your Personal Savings Allowance (PSA) can't be carried forward, receiving several years' worth of interest in one tax year could mean you exceed your allowance and pay tax on some of the interest. In some cases, it could even push you into a higher tax band for that year.
It won't affect everyone, but it's certainly something worth considering before deciding how you'd like your interest paid.
Are the new rates competitive?
The latest increases undoubtedly make NS&I more competitive, especially when compared with many of the high street banks.
However, savers prepared to look beyond the familiar names can still find significantly better returns elsewhere.
For example, a £50,000 deposit for 12 months would earn £2,345 (before the deduction of tax) with NS&I’s 1-year bond, compared with £2,450 with Marcus: from Goldman Sachs, which currently pays 4.90% AER.
It's the same with the longer fixed terms. The top 2-year bond is paying 4.86% versus the NS&I bond paying 4.67% Over 3-years, the top rate is 4.85% compared to 4.65% with NS&I and over 5-years you can earn up to 4.90% compared to NS&I’s option which is now 4.55% AER
So, whilst NS&I’s new rates have improved, they don’t make it into the best-buy tables.
Despite rarely topping the tables, NS&I continues to benefit from huge customer loyalty. A key reason is its unique Government guarantee. Every penny held with the provider is backed by HM Treasury, giving savers complete protection, regardless of how much they hold.
You can invest £500 up to £1 million into each issue of the British Savings Bonds, making them particularly appealing for those with larger sums who prioritise safety over the best returns.
For most savers, though, whose balances fall below the £120,000 Financial Services Compensation Scheme (FSCS) protection limit that applies to all other regulated and authorised banks and building societies, there are still better-value options elsewhere.
*Bank of England Table A7.1 (changes tab)
For the latest rates, visit our Best Buy tables.
Arrange a free initial consultation
Rates correct 02/07/2026
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions. The Financial Conduct Authority (FCA) does not regulate tax advice.
The cost of Inheritance Tax gift mistakes soars to £336m
HMRC collected an estimated £336 million in inheritance tax (IHT) over the past five years from failed gifting arrangements, after the assets involved were deemed not to have been fully given away.
Between 2021 and 2026 nearly 2,500 gifts with a combined value of £840 million were classed by HMRC as gifts with “reservation of benefit”. This applies where the person making the gift continues to enjoy some benefit or use of the asset after it has been passed on.
As a result, these gifts, which had an average value of £338,840, did not qualify for inheritance tax exemption and left families facing an estimated £336 million tax charge.
What is a gift with reservation of benefit?
A gift with reservation of benefit essentially means when someone gives away an asset but continues to enjoy, or is able to enjoy, some benefit from it. The classic example is a person who gives their house to their children but continues to live in it rent-free.
As a result, the gift is not regarded as an effective lifetime transfer for inheritance tax purposes. Instead, the asset – the house in the above example - is treated as remaining within the donor’s estate when they die, meaning its full value is included in the inheritance tax calculation. The asset may also be subject to tax again on the death of the recipient.
What counts as the gifter still ‘benefitting’ has a fairly wide definition and applies to many other assets too. Examples include handing over valuable possessions while still making regular use of them and transferring shares in a family company while keeping the right to receive dividends or exercise voting power. In these situations, the legal ownership may have changed, but the donor is still considered to retain an interest in the asset. It is important to understand whether you will be classed as still ‘benefitting’ from the asset you have gifted before you go ahead and ‘gift’.
You can find out more about gifts without reservation of benefit here.
Why are IHT receipts always on the rise?
Total IHT receipts collected by the Government has been steadily on the rise since the IHT threshold freeze and are showing no signs of slowing.
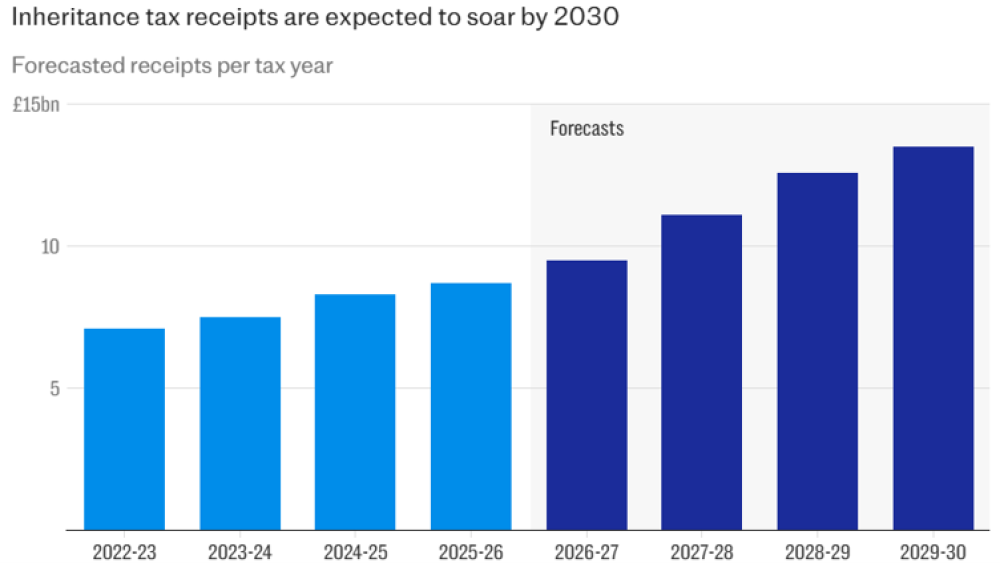
Source: Inheritance tax receipts are expected to soar, OBR, 2023
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026.
However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this move an example of a ‘stealth tax’, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if it indeed does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the UK taxpayer.
The inheritance tax allowance of £325,000 increased from £312,000 on 6 April 2009. This means the IHT nil rate band has now been frozen for over 15 years and will continue to be frozen until at least 5 April 2031. Though some additional relief was introduced in April2017 through the residence nil rate band, which can increase the tax -free allowance where a main home is passed to direct descendants, the main nil rate band itself will have been frozen for a staggering 22 years of higher taxes on death - over two decades.
If you’re interested in how to manage your inheritance tax to ensure the best possible wealth protection for you or your family, we can help. Give us a call on 0333 323 9065 or book a free non-committal initial consultation with a member of our team to find out more.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax advice.
The Stealth Tax Squeeze
A new report has highlighted the growing impact of frozen tax allowances in the UK, with some thresholds remaining unchanged for more than four decades.
Research from Association of Taxation Technicians (ATT) found that numerous allowances have remained static for decades, resulting in taxpayers paying more in real terms without any formal increase in tax rates – a policy by the Government known more informally as ‘stealth tax’.
ATT argues that many tax reliefs are overdue a comprehensive review, as years of inflation have steadily reduced their real-world value through fiscal drag.
So, who’s being affected by ‘stealth taxes’?
Almost everyone will in some way or another be losing money to stealth taxes.
Inheritance tax provides some of the clearest examples. The nil-rate band, which determines how much of an estate can be passed on free from inheritance tax, currently remains at £325,000 per individual. This threshold was last increased 17 years ago and is now scheduled to stay frozen until 2031. According to the ATT report, if it had been adjusted in line with inflation, it would stand at approximately £525,000 today, around 60 per cent higher than its current level.
The same pattern can be seen across other inheritance tax exemptions. The annual gifting allowance has been fixed at £3,000 since 1981. Using the Bank of England’s inflation calculator, the ATT estimates that an inflation-linked equivalent would now be around £11,800, almost four times the existing allowance.
Meanwhile, the wedding gift exemption has remained unchanged at £5,000 since 1975, having originally been introduced under the capital transfer tax regime before inheritance tax existed in its current form. Had it increased in line with inflation over that period, it would now be worth £39,876, representing a rise of 697 per cent. With UK weddings in 2026 costing on average an eye watering £20,604, that missed 697 per cent will come with an especially nasty sting for newly weds.
The report also found that savers have been affected by the same phenomenon. Basic-rate taxpayers can currently receive up to £1,000 of savings interest tax-free under the personal savings allowance, while higher-rate taxpayers are entitled to £500. Had these limits risen alongside inflation since their introduction in 2016, they would now be worth roughly £1,400 and £700 respectively.
Homeowners benefiting from the Rent a Room scheme have also seen the value of their tax break eroded. The scheme's £7,500 tax-free income limit has not increased since 2016. If it had kept pace with inflation, it would now be closer to £10,500.
Not even those saving into their pensions have been able to escape the stealth tax net. Individuals without relevant earnings can contribute £2,880 each year to a pension, which becomes £3,600 after tax relief is added. This allowance has remained unchanged since 2000. If uprated for inflation, it would be approximately £5,500 net, or £6,850 including tax relief.
The forever frozen allowances
It has become the new norm for each Government to announce a further freeze on allowances, kicking the can down the road with each successive freeze, all the while taxpayers are being forced to hand over increasing amounts as fiscal drag pulls them ever further beyond the outdated thresholds.
One example of this is inheritance tax (IHT). Total IHT receipts collected by the Government has been steadily on the rise since the IHT threshold freeze.
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026. However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this a clear example of stealth taxes, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if it indeed does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the taxpayer.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered financial advisers to find out how can help.
Arrange a free initial consultation
The Financial Conduct Authority (FCA) does not regulate cash flow planning, tax or estate planning.
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.