Skip to main content
Budget rumours? Don't panic.
It is not long until Chancellor John Healey’s first budget on 28 October 2026 and you may be wondering if you need to take any action ahead of this.
Newspaper speculation ahead of previous budgets has been rife, with rumours that tax free cash entitlements will be reduced seeming to surface around this time every year. Some pension holders seem to have been taken in by this speculation in previous years; a recent Sky News article revealed £91.2bn was withdrawn from pensions accessed for the first time in 2025/26, up from £53.6bn in 2023/24. However, some people may be regretting their decision to take money out of their pension, given they may have moved funds from a tax free environment within their pension into a taxable environment outside it.
Arrange your free initial consultation
Pensions minister Torsten Bell clearly finds the speculation unhelpful, describing misleading stories as ‘disgraceful’ and ‘garbage’ in a recent Citywire article.
Even if there are no changes to tax free cash entitlements announced in the budget, we are getting closer to the implementation date for a big pension change that has already been announced; that defined contribution pensions will form part of estates for inheritance tax (IHT) purposes from April 2027. Pensions should be reviewed ahead of this, specifically:
- The nomination of beneficiaries for pensions - if a married couple are planning to leave their pension to their children rather than each other, this could become tax inefficient in April 2027.
- The interaction between pension nominations and wills - especially when these are not being left to the same beneficiary. As inheritance tax will be proportioned between the pension and the estate, the net amounts each beneficiary receives may change overnight on 5 April 2027.
- Gifting to charities – again the best way to do this may change. Estates benefit from a reduced inheritance tax rate of 36% when over 10% of the taxable net estate is left to charity, but pension death benefits from April may be subject to IHT and income tax, so it could be the case that leaving part of the pension to charity rather than part of the rest of the estate may become the better option.
However, those aged under 75 who are married or in civil partnership should not panic, as upon their death they can leave their pension to their spouse/civil partner under the spousal exemption and their spouse/civil partner can in turn draw from the pension tax free. Longer term however, consideration could be given if appropriate, to drawing from the pension to create excess income that can be gifted away under the regular gifts out of surplus income IHT exemption as the individual approaches age 75, at which point the tax rules change.
In terms of changes that could be announced:
- Prime Minister Andy Burnham has signposted a new ‘Your First Home’ scheme to help first time buyers get on the housing ladder.
- There are rumours that capital gains tax (CGT) could be increased. The level and timing of the increase would be important if this does happen, as there are question marks over the increased revenue that is actually raised by increasing CGT, given individuals can choose to hold onto assets and not sell them if increases to CGT rates are significant. However, if a change is announced to take effect in April 2027, this gives individuals the chance to sell assets before the higher rate kicks in which could lead to an increase in activity.
- As has been the case in previous years, the chancellor has the option to freeze tax bandings further into the future.
To summarise, Torsten Bell’s comments indicate he is hoping not to see the same level of pre-budget speculation as previous years and investors have often seen sub-optimal outcomes after making decisions based on speculation alone. Therefore, we will need to wait until after the budget to decide if any action is required as a result of any newly announced changes, alongside already known:
- Fiscal drag caused by frozen tax thresholds until 2031
- Upcoming increases to property income and savings tax rates in April 2027
- Cash ISA changes which will limit contributions from next year and mean that individuals looking to transfer their Stocks and Shares ISA into Cash ISAs must do so by April 2027
- Mansion tax due to take effect in April 2028
- Salary sacrifice National Insurance saving contribution limit of £2,000 to take effect from April 2029
If you would like to discuss the implications of the upcoming changes, please contact get in touch to see how we can help.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate estate planning, wills or tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available. Your pension income could also be affected by the interest rates at the time you take your benefits.
UK State Pensions triple lock to be scrapped
Following the Labour Conference in Liverpool, the state pensions triple lock will be scrapped in place of a double lock, according to prime minister Andy Burnham.
Burnham explained that from April 2030, the state pension would continue to rise each year by 2.5% or inflation, whichever is highest, but would no longer be matching earnings – the original third guarantee of the triple lock.
‘It will hold its value relative to earnings over time so that pensioners will always share in the rising prosperity of the nation. This change will generate significant savings, which we will use to build up our own National Care Service,’ Burnham told the Conference.
Burnham went on to compare the policy as one that was as significant as the ‘creation of the NHS itself’.
The triple lock is considered a gold standard for pensioners in the UK, which represent a large voter base, and as such governments have been reluctant to touch it despite a heated debate continuing around its fairness after so many years since its introduction by the Conservative-Liberal Democrat coalition government back in 2011.
Regardless of which side of the debate people fall on, it is clear that the scrapping of the triple lock represents a bold move by Burnham’s government.
"Retaining the inflation link will be comforting to current and future pensioners and if giving up the earnings link provides savings which can be directed towards the chronically underfunded care system then this will be welcomed by many. However, the devil is always in the detail and we eagerly await the promised detail in the next Parliament." – Jane Reade, Head of Financial Planning at The Private Office (TPO).
The 'Triple Lock' explained
The ‘triple lock’ refers to a well-known state pensions policy that ensures state pensions rise every year by either the average earnings growth, inflation (as measured by the Consumer Prices Index) or a flat 2.5% - whichever is highest that year, hence the name ‘triple’ lock.
It was designed in principle to make sure that state pension value would always have the best growth outcome each year for pensioners. The guarantee that the highest of the three will be what pensions grow against ensures that savers have three layers of protection against inflation. This is incredibly important in maintaining a level of healthy financial security for those relying on their pensions, as it guarantees growth irrespective of how volatile the economy becomes.
If you want to find out more about retirement planning, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered advisers to find out how we might be able to help you.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
Back to the future for pensions
After 40 years in the industry, I will be hanging up my boots at the end of the year and taking up a new career on the golf course.
To say that I’ve seen a few changes in that time is an understatement but now, at the end of my career, I’ll take one last spin in the DeLorean and look at the twists and turns that pensions legislation has taken over the last four decades and how that has affected my clients.
Arrange your free initial consultation
The first thing I’d like to say is to offer my sympathies to the general public who have been subjected to rules and complexities which should really be the preserve of rocket science. The opaqueness of pensions has been a disservice to the consumer and for many, this lack of clarity has resulted in rejection. I really don’t blame anyone for this. I have a similar reaction if, for instance, I’m trying to work out which mobile phone package is best. In the end, there is a tendency to turn your back on the whole subject for fear of doing the wrong thing.
But let me make one thing clear. Pensions are, and always have been, the most tax efficient means of saving for retirement.
Stepping back to 1987
If I set my clock to 1987 and step out of my time machine, apart from the padded shoulders, I’m struck by the fact that full tax relief is available on contributions (up to a limit). This is still the case now and if I can say what the most common question clients ask just before a budget it’s “Do you think they will take away higher rate tax relief on pensions?”. Here I am, nearly 40 years later and this highly attractive property of pensions remains intact, yet I expect one last wave of this question before this, my final budget as an advisor.
Tax relief was even more attractive back then because income tax was higher. Who would turn their nose up at the opportunity to invest £40 and for it to be immediately worth £100 (the higher rate of income tax was 60% in 1987)? Many did though. Maybe they thought it was too good to be true. But it was!
In those days, personal pensions were mostly found amongst the self-employed as employed people often enjoyed final salary pension schemes. Over the years, final salary schemes have been culled from the private sector (they’re simply too expensive for employers to run). Now, unless you’re in the public sector, final salary pension schemes are like hens’ teeth.
What happened to pensions from 1995
Let’s get back in the DeLorean and get out in 1995. Until then personal pensions were restricted in that you had to buy an annuity when you retired. This was all very well and meant people didn’t have to worry about investment returns. Annuity rates were also high (although this really only reflected the fact that we had double digit inflation). By 1995, however, rates were reducing and there was growing unrest driven by the prospect of parting with your pension pot in exchange for a low annuity return. So, under John Major’s government, income drawdown was introduced and for the first time pension holders were allowed to keep their funds invested and take an income (within upper and lower limits). As gilt rates (and annuity rates) continued to tumble, we never looked back and drawdown was here to stay (albeit with some horror stories around high-risk portfolios suffering in subsequent market crashes).
Things bumbled along fairly uneventfully for the next twenty years but, in all this time, pensions were never attractive from an estate planning point of view, and nobody ever thought of them in this way. There were all sorts of complex rules which I have no intention of repeating here but, in essence, if pensions were left to anyone other than a spouse there was punitive tax. It was only when George Osborne announced pensions freedom in 2015 that the idea of pensions ‘cascading’ down the generations was invented. Before George, pension funds attracted a fairly hefty tax on death of 55%. Earlier than that and it could have been more, up to 82% in some circumstances. All of a sudden, there was no tax at all and pension funds, particularly for the very wealthy, were now parked for future generations. Furthermore, you could take the whole fund as drawdown. There was a lot of talk about Lambourghinis but, in truth, no one really wanted to draw out so much that they were subject to higher rate income tax.
Then came the Budget in 2024
Which brings us to the present and in 2024 Rachel Reeves announced that pensions would be subject to Inheritance Tax from 2027. Let’s put this into perspective and compare the taxation of a personal pension from 2014 to a pension in 2027. Let’s say leave it to your children as pensions passing to spouses is exempt from IHT. In 2014 it would have been subject to a 55% tax (if in drawdown) so they would end up with 45% of the fund. In 2027 there will be IHT, say 40% if the rest of the estate is substantial enough to use up the Nil Rate Band. This means that 60% is inherited but this, in turn, could be subject to income tax if they die after the age of 75. Let’s say the children are basic rate taxpayers. This means they will inherit, after tax, 48% of the fund compared to 45% in 2014.
There are, of course, situations where it is more punitive now (particularly if the children are higher rate) but the point is that in 2027 most people will be in a similar situation to tax legislation of 2014.
Will the government take away tax-free cash on pensions?
I think the second most common question I’ve had over the forty years is “Will they take away the tax free cash?”. True, it has been capped to the distinctly catchy number of £268,275 but, for most, it still stands at 25% of the fund. Will it be reduced further? Alas, I cannot go into the future, only the past. If I could have, I wouldn’t be here, would I? So, your guess is as good as mine.
In the final analysis, I would say that pensions are more attractive now than they were forty years ago. They are more flexible. Pensions are still inheritable, albeit distinctly less attractive from 2027. They are also cheaper to run. In the 80s most pensions were only available from insurance companies and charges were punitive. These days, plans are cleaner and don’t have initial charges. There is also much more choice of investment, not just a few vanilla funds. Drawdown is definitely a huge advantage, removing the compulsion to buy annuities. I should mention that you still can buy annuities and people still do, in certain circumstances. You could even have both annuity and drawdown.
But with more flexibility comes more responsibility. Good advice is absolutely essential, particularly when in drawdown. The greatest danger to any fund, from which meaningful withdrawals are being made, is something called Sequence Risk. This is the damaging effect on a portfolio if it is all invested in risk funds, and withdrawals are taken at the bottom of the market. A good adviser will recommend holding different risks for different timescales to negate this risk.
So, it’s time for me to forget about the past and buckle into the DeLorean to see what the future holds. I will now become a client of TPO and will see where the road takes us although, as Emmet Brown said “Where we’re going Marty, we don’t need roads”.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available. Your pension income could also be affected by the interest rates at the time you take your benefits.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
Are you prepared to die?
Passing away without adequate preparation carries a heavy price tag. Beyond the obvious costs of a memorial service or burial, families face substantial hidden financial and emotional burdens when they overlook proper estate planning. Key oversights such as omitting a valid Will, failing to register a Lasting Power of Attorney, leaving cohabiting partners without legal protection, or leaving financial gifts incomplete can inevitably increase the strain on grieving loved ones.
Research we recently conducted, alongside government and industry data, shows just how widespread this unpreparedness is in the UK – and how much it can cost, in time, money and stress, when families are left to work it out on their own.
Arrange your free initial consultation
How prepared are we, really?
On paper, most people know they should plan ahead. In practice, most haven't. A study by the Money and Pensions Service revealed that 56% of adults in the UK lack a will, with 53% of individuals aged 50–64 falling into this category – an age group where concerns about death and incapacity shift from distant thoughts to a closer possibility. This is also the period of time often referred to as “Sniper's Alley”, when people face a sharply increasing risk of serious health conditions. Without a will, the law decides who inherits, not the person who died – and the rules rarely match what people actually intended.
The preparedness gap extends to digital assets too. A survey by consumer group Which? found that 76% of people have left no plan for what happens to their digital assets when they die. This is especially concerning when finances are involved, with research from Finder, a financial comparison and consumer education platform, estimating that 50.1 million people in the UK now use some form of online or remote banking; that's 91% of the adult population. With many having a digital footprint spanning multiple logins, accounts and portals, often with no record of them held anywhere accessible, for families trying to settle an estate, tracking down that information can add weeks of stress on top of grief.
The gap is even wider when it comes to understanding legal protection within relationships. A Ministry of Justice consultation found that 47% of people in England and Wales believe "common law marriage" exists and gives legal protection after a set number of years together. It doesn’t and never has. With 3.5 million people now cohabiting outside marriage or a civil partnership, and fewer than half of UK adults married or in a civil partnership, that misconception leaves millions exposed. Under current intestacy rules, an unmarried partner has no automatic right to inherit anything from their partner's estate, regardless of how long they lived together or how finances were shared - a protection that at least the children can receive.
Without a will, even a decades-long partnership offers no legal protection. It is one of the starkest examples of what being unprepared can cost the people you leave behind. Even if a will does leave everything to an unmarried partner, there is no Inheritance Tax (IHT) spousal exemption, so IHT would need to be paid, unlike when assets are left to a spouse or civil partner, when there is no IHT payable.
The Private Office's (TPO) own survey of 2,126 UK adults*, mostly aged 45 and over, found that gifting early is desirable. The overwhelming majority, 80.7%, believe wealth should be passed on to the next generation during their lifetime rather than left to inheritance – 67.9% see helping with a first home as the moment support matters most.
Yet many hold back. Retirement security and long-term care costs together account for over half of the concerns people give when asked what stops them from gifting more or gifting at all, demonstrating that financial uncertainty in later life remains the biggest barrier to gifting. It is a solvable problem, however; those who plan early and build a clear picture of their future financial needs are far better placed to gift with confidence, knowing what they can afford to give without compromising their own security and hopefully leaving less tax for their loved ones to pay on their death.
| Top barriers to early gifting | % |
|---|---|
| Running out of money later in retirement | 37.3% |
| Care home costs | 15.5% |
| No concerns | 15.0% |
| Money won’t be used responsibly | 11.5% |
| Inheritance tax concerns | 10.7% |
| Economic uncertainty | 4.7% |
| Family disputes | 2.3% |
What being unprepared actually costs
Delay becomes deputyship. Without a registered Lasting Power of Attorney, a family that needs to manage a loved one's finances or care decisions after they lose mental capacity has to apply to the Court of Protection instead. Registering an LPA in good time costs £92; applying for deputyship after capacity is lost costs £400 – before factoring in the months it can take to get a court order in place, during which bills, care fees and property costs still need to be paid. Over a million LPAs were registered with the Office of the Public Guardian in 2023–24, a rise of more than 30% since 2019–20, showing more people are waking up to this – but the majority still haven't.
No will means no control, and often, no speed
When someone dies without a valid will, their estate is distributed under intestacy rules, which take no account of unmarried partners, stepchildren, or personal wishes. It also tends to take longer: according to DNA Legal, the number of probate cases taking over a year to resolve has risen 518% in five years, from 377 in 2019 to 2,328 in 2024, as estates become more complex and more contested.
Being unmarried carries a real financial cost
This is an increasingly significant issue given the growth in cohabiting families, which now number around 3.5 million in 2025, more than double the figure 30 years ago. For cohabiting couples, the absence of a will could mean losing a home they've lived in for decades if it isn't owned on a joint tenancy basis. A recent government consultation, which closed on 14 August 2026, examined whether unmarried partners should gain automatic inheritance rights if their partner dies without a will – a sign of how significant a gap this has become, but a change that, if it happens at all, is still some way off. For now, the only real protection is a will, and ideally a cohabitation agreement, drawn up in advance.
Gifting that stalls costs the giver peace of mind and the recipient certainty
TPO’s survey found that among people who haven't yet gifted, 39.7% still intend to – but uncertainty about their own future costs, particularly care, is often what stops a gift from being made or completed, while it would still help most. A gift promised but never followed through leaves both generations in limbo: the older generation still carrying the asset (and the tax exposure) they meant to pass on, and the younger generation still without the support they thought they could expect.
Practical steps: what "prepared" actually looks like
None of this requires anything dramatic – just a small number of documents and decisions, made once and reviewed regularly.
- Make a will and review it after any major life event – moving house, starting a new relationship, the arrival of a child, or the death of someone close. This is the biggest single gap in UK planning and the easiest to plug. Free Wills Month is a UK campaign run twice a year, in March and October, giving people aged 55+ the chance to have a simple will written or updated by a solicitor free of charge.
- Register a Lasting Power of Attorney for both property and financial affairs and health and welfare while you have full capacity to do so. It's a fraction of the cost and the stress of a deputyship application made in a crisis.
- If you're cohabiting, don't rely on "common law marriage." A will that names your partner, and a cohabitation agreement setting out how shared assets are treated, are currently the only reliable protections.
- If you're planning to gift, plan the whole gift, not just the giving. Whether it's help with a deposit, a contribution to a pension, or money into a Junior ISA or trust for a grandchild, working out what you can afford to give, and keeping that separate from what you might need for your own care, turns a gift into a plan rather than a decision made under pressure. Don’t forget that if you can make use of the 7 year rule and/or gift money out of surplus income, this can reduce the IHT liability to your loved ones.
- Create a digital death file. A will and an LPA tell people what to do, but they still need to be able to find the accounts, documents and contacts to act on those wishes. A secure digital file, one that stores your will, any trust details, tax information, professional contacts and emergency details, and that trusted people know how to access, removes a significant burden from the people left behind. You can also name a digital executor in your will to give someone specific responsibility for managing online accounts and digital assets. Without one, families can be left chasing logins and account details at exactly the moment they are least equipped to do so. At The Private Office, all clients have access to TPO Wealth, a secure online portal that acts as a digital filing cabinet for exactly this purpose, at no additional cost.
- Talk to your family about what you've decided, not just to a solicitor. Most of the stress in these situations comes from people finding out too late, not from the decisions themselves.
- Be aware of changes we know are coming. From April 2027, unused pension funds will form part of your estate for inheritance tax purposes, which is precisely why being prepared matters. Not only is this likely to bring more people into the IHT trap - and subject some beneficiaries to income tax as well as IHT - but it will also increase the burden on executors, who will need to account for all pensions held at the time of death. Having your affairs in order, with clear records of every pension you hold, is no longer just good practice; it is something your loved ones will be grateful for. It’s also essential to review who you have nominated your pension to on your death, as the new rules could mean that you might want to change your mind.
Having Peace of Mind
The more assets a family has, the more moving parts there tend to be – pensions, property, trusts, gifting plans – and the more those decisions need to work together rather than being made one at a time.
Talking about what happens when we die is never easy, and it’s understandable that people put it off. But from our experience, the biggest cost of not having these conversations is not only the financial cost, but the additional stress and uncertainty placed on the people we leave behind.
When a family is already dealing with the loss of someone they love, having to untangle their financial affairs or discover that arrangements weren’t quite what they thought, can make an incredibly difficult time even harder.
The good news is that getting your affairs in order doesn’t have to be complicated. A valid will, appropriate powers of attorney, clear records of your finances and some thought about how and when you want to pass on your wealth can make a significant difference.
It’s also important to look at these things as part of one overall plan, rather than as isolated decisions. Taking a little time now to understand what you have, what you want to happen and what your family might need means you can make those decisions on your own terms, rather than leaving them to others at a much more difficult time.
If you're not sure where your own plans stand, or it's been a while since you looked at them, talk to one of our advisers about reviewing them.
*The findings are drawn from a survey of 2,126 The Private Office newsletter subscribers, conducted in May 2026. The sample is weighted heavily towards older, asset-rich homeowners, reflecting the demographic most likely to be engaged in intergenerational wealth transfer. Respondents skewed towards the 65 and over age group (77% of the sample), with 40.1% aged 65 to 74 and 36.9% aged 75 and over. The remaining respondents were aged 55 to 64 (18.2%), 45 to 54 (3.8%) and under 45 (1.0%). In terms of housing status, 91.3% were outright homeowners, 5.5% held a mortgage, 1.4% rented privately, and 1.8% fell into other categories. 75.3% of respondents had children, grandchildren, or both.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
The Financial Conduct Authority (FCA) does not regulate cash flow planning, estate planning, tax or trust advice.
State Pension to be taxed following rise
The full State Pension is due to rise to above £13,000 a year, raising fresh questions about the growing cost of the system and fairness between generations.
Under the ‘triple lock’, payments rise by whichever is highest of average wage growth, inflation or 2.5%.
The latest figures from the Office for National Statistics (ONS) showed total wage growth, including bonuses, stood at 3.9% in the quarter to July, down from 4.2% in the three months to June. These earnings figures would mean the full, flat rate State Pension would increase by 3.9% or £488 next April to £13,036.40.
However, this won’t be locked in until the inflation figures for September are published in October, as they could in theory be higher than the 3.9% taken from total wage growth. The inflation figures for August were released on Wednesday, showing that inflation had risen to 3.1% in the 12 months to August, up from 2.9% in July.
The State Pension age is rising to 67 in April 2028, but government spending continues to increase. The annual State Pension bill is expected to reach £154bn this year and could rise by a further £600m a year by 2029/30 according to estimates.
Economists have raised concerns about the cost of the State Pension ahead of the Budget, as with this raise, pensioners are beating headline inflation at a time when many are struggling to keep pace, while pensioner groups argue that many older people still face poverty. Additionally, with this increase, the State Pension will breach the personal allowance threshold, making it in theory liable to be taxed.
The ‘Triple Lock’ explained
The ‘triple lock’ refers to a well-known State Pensions policy introduced in 2010 by the Conservative and Liberal Democrat Coalition Government that ensures State Pensions rise every year by either the average earnings growth, inflation (as measured by the Consumer Prices Index) or a flat 2.5% - whichever is highest that year, hence the name ‘triple’ lock.
It was designed in principle to make sure that State Pension value would always have the best growth outcome each year for pensioners. The guarantee that the highest of the three variables will be what pensions grow by ensures that Pensioners have three layers of protection against inflation, hence the name ‘triple lock’. This is incredibly important in maintaining a level of healthy financial security for those relying on their pensions, as it guarantees growth irrespective of how volatile the economy becomes.
If you want to find out more about retirement planning, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered financial advisers to find out how we might be able to help you.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
Over a million pensioners pushed into higher rate tax
The number of pensioners paying higher rate tax has doubled in the past five years, according to a recent freedom of information (FOI) request from Sir Steve Webb, UK's former Minister of State for Pensions.
Now, over a million pensioners are paying higher rate tax or more this year, up from half a million in 2021-22, with the number of pensioners paying additional rate tax, a tax band originally intended for only the highest earners in society, having trebled during the same timeframe.
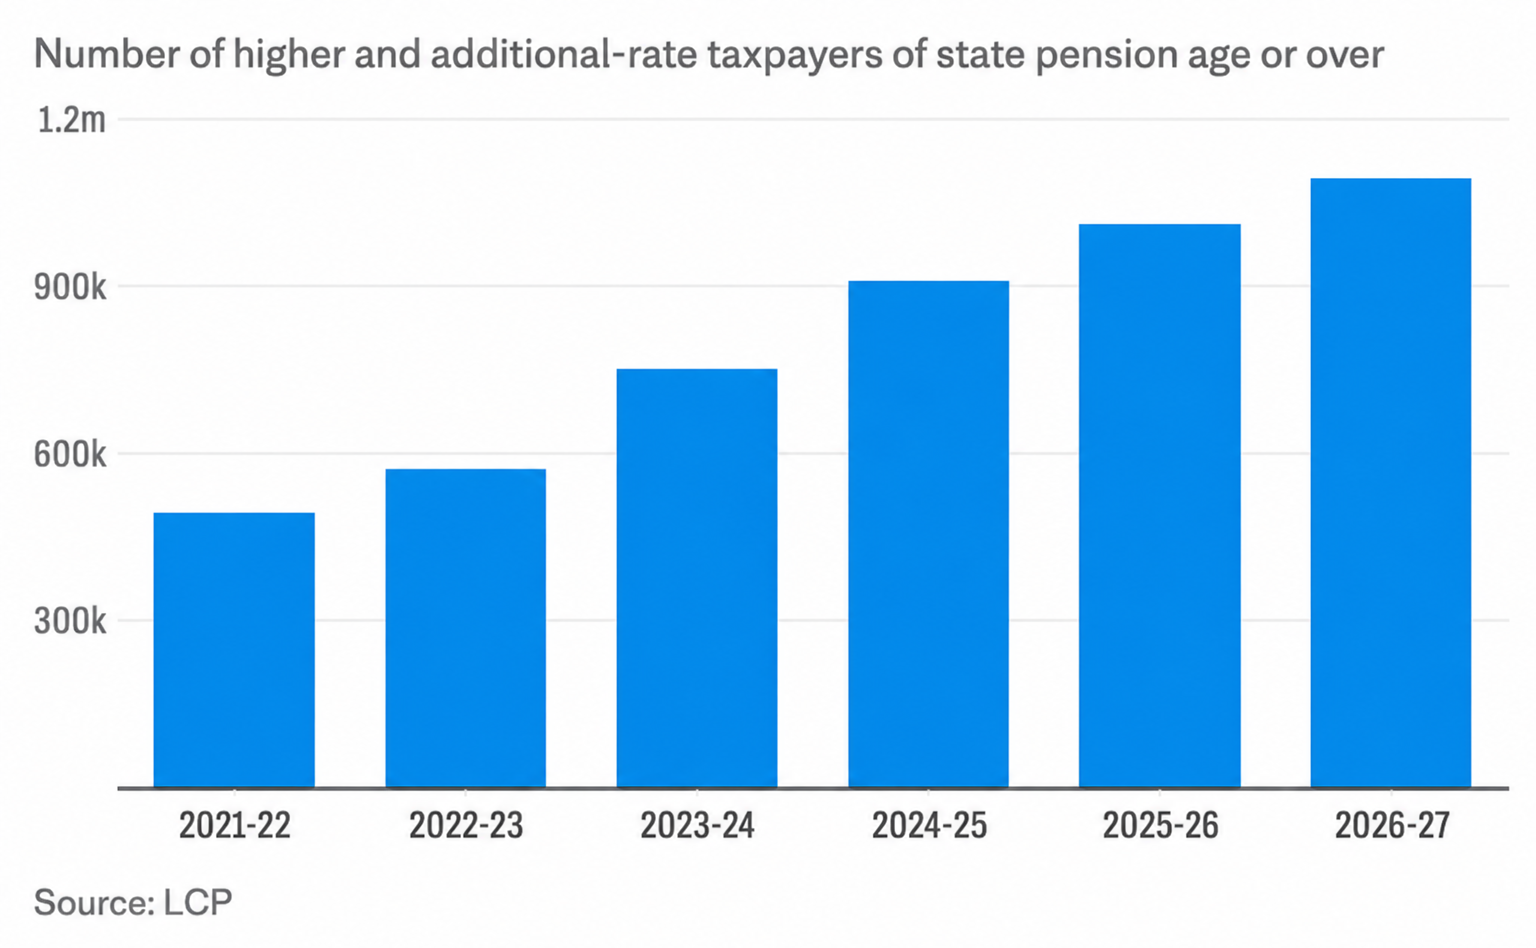
Once again, frozen thresholds or ‘stealth taxes’ are at the root of the issue, as the net widens, capturing more pensioners in the higher rate tax bands. According to the FOI data, the number of pensioners paying higher and additional rates of income tax has risen as state pension incomes increase in line with inflation while income tax thresholds remain frozen.
With thresholds set to stay at their current levels until April 2031, more retirees are likely to find that growing state and private pension income takes them into higher tax bands.
As this continues, it is likely to affect retirement planning for many workers. If a greater share of pension income is lost to tax, people may need to build up larger pension pots and savings during their working lives to achieve the level of income they want in retirement.
Arrange a free initial consultation
The forever frozen allowances
It has become the new norm for each Government to announce a further freeze on allowances, kicking the can down the road with each successive freeze, all the while taxpayers are being forced to hand over increasing amounts as fiscal drag pulls them ever further beyond the outdated thresholds.
One example of this is inheritance tax (IHT). Total IHT receipts collected by the Government has been steadily on the rise since the IHT threshold freeze.
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026. However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this move an example of ‘stealth tax’, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if indeed it does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the taxpayer.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered advisers to find out how can help.
Arrange a free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available.
Your pension income could also be affected by the interest rates at the time you take your benefits. The tax implications of pension withdrawals will be based on your individual circumstances, tax legislation and regulation which are subject to change. You should seek advice to understand your options at retirement.
Families hit by inheritance tax on pensions
From next April, grieving families will not only be taxed on their loved one’s pensions, but will also be prevented from claiming loss reliefs on those pension pots under new planned taxation rules.
Under these plans, estates could face higher tax bills and extra late payment interest at the worst possible time while dealing with a bereavement.
Previously, pension pots were exempt from inheritance tax (IHT) and not included in the taxable estate after someone died, but following an announcement last year from former chancellor Rachel Reeves, pension pots will now be included in an individual’s estate from April 2027, meaning they will be subject to IHT on death like any other part of an estate.
Currently, if an asset is sold at a loss within 12 months of the death, family members are entitled to reclaim the difference in tax from HM Revenue & Customs (HMRC) through “loss on sale relief”. However, the same rule will not apply to pensions if they fall in value.
HMRC confirmed that certain IHT reliefs will not apply to unused pension assets as the deceased isn’t classed as owning the assets before death, despite being taxed like the rest of the estate. Executors will be unable to claim loss on sale relief, business property relief, agricultural property relief or pay inheritance tax by instalments on qualifying pension assets, despite those reliefs remaining available for assets held outside pensions.
There is concern that this could create a 'two-tier' system, where pensions will have less protections from tax.
What is inheritance tax?
Inheritance Tax (IHT) is a tax levied by the Government on the estate of a deceased person in the UK. This covers all of their assets including property, personal belongings, investments and, from April 2027, it also includes pensions.
However, this levy only applies to the total value of the estate that exceeds the IHT threshold or ‘nil-rate band’. As of the 2025/26 tax year, the threshold is set at £325,000. Anything above £325,000 could be subject to up to 40% inheritance tax and anything below this threshold is tax-free. In addition, an extra allowance known as the residence nil rate band (RNRB) of up to £175,000 may apply when a main home is passed to direct descendants, potentially increasing the total tax-free threshold to £500,000 for an individual.
Traditionally pensions have been exempt from inheritance tax but, from April 2027, pensions will no longer have this exempt status. This means that inheritance tax may have to be paid on your pension when you die.
If you’re interested in how to manage your inheritance tax to ensure the best possible wealth protection for you or your family, we can help. Give us a call on 0333 323 9065 or book a free non-committal initial consultation with a member of our team to find out more.
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The Financial Conduct Authority (FCA) does not regulate tax advice.
A pension is a long-term investment not normally accessible until age 55 (57 from April 2028 unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up which would have an impact on the level of pension benefits available.
The Stealth Tax Squeeze
A new report has highlighted the growing impact of frozen tax allowances in the UK, with some thresholds remaining unchanged for more than four decades.
Research from Association of Taxation Technicians (ATT) found that numerous allowances have remained static for decades, resulting in taxpayers paying more in real terms without any formal increase in tax rates – a policy by the Government known more informally as ‘stealth tax’.
ATT argues that many tax reliefs are overdue a comprehensive review, as years of inflation have steadily reduced their real-world value through fiscal drag.
So, who’s being affected by ‘stealth taxes’?
Almost everyone will in some way or another be losing money to stealth taxes.
Inheritance tax provides some of the clearest examples. The nil-rate band, which determines how much of an estate can be passed on free from inheritance tax, currently remains at £325,000 per individual. This threshold was last increased 17 years ago and is now scheduled to stay frozen until 2031. According to the ATT report, if it had been adjusted in line with inflation, it would stand at approximately £525,000 today, around 60 per cent higher than its current level.
The same pattern can be seen across other inheritance tax exemptions. The annual gifting allowance has been fixed at £3,000 since 1981. Using the Bank of England’s inflation calculator, the ATT estimates that an inflation-linked equivalent would now be around £11,800, almost four times the existing allowance.
Meanwhile, the wedding gift exemption has remained unchanged at £5,000 since 1975, having originally been introduced under the capital transfer tax regime before inheritance tax existed in its current form. Had it increased in line with inflation over that period, it would now be worth £39,876, representing a rise of 697 per cent. With UK weddings in 2026 costing on average an eye watering £20,604, that missed 697 per cent will come with an especially nasty sting for newly weds.
The report also found that savers have been affected by the same phenomenon. Basic-rate taxpayers can currently receive up to £1,000 of savings interest tax-free under the personal savings allowance, while higher-rate taxpayers are entitled to £500. Had these limits risen alongside inflation since their introduction in 2016, they would now be worth roughly £1,400 and £700 respectively.
Homeowners benefiting from the Rent a Room scheme have also seen the value of their tax break eroded. The scheme's £7,500 tax-free income limit has not increased since 2016. If it had kept pace with inflation, it would now be closer to £10,500.
Not even those saving into their pensions have been able to escape the stealth tax net. Individuals without relevant earnings can contribute £2,880 each year to a pension, which becomes £3,600 after tax relief is added. This allowance has remained unchanged since 2000. If uprated for inflation, it would be approximately £5,500 net, or £6,850 including tax relief.
The forever frozen allowances
It has become the new norm for each Government to announce a further freeze on allowances, kicking the can down the road with each successive freeze, all the while taxpayers are being forced to hand over increasing amounts as fiscal drag pulls them ever further beyond the outdated thresholds.
One example of this is inheritance tax (IHT). Total IHT receipts collected by the Government has been steadily on the rise since the IHT threshold freeze.
This was initially announced by the then Chancellor, Rishi Sunak, in his 2021 Budget. The Budget outlined that the IHT threshold would be frozen for five years until 2026. However, after ex-Chancellor Jeremy Hunt’s 2023 Autumn Statement, it was confirmed that the freeze would be extended a further two years until April 2028, and then after Rachel Reeves’ 2024 Autumn Statement, this was extended once again a further two years until April 2030, and finally after her 2025 Autumn budget, it was again extended, this time until April 2031.
Many have been calling this a clear example of stealth taxes, as the freeze ultimately means an increasing number of Britons will fall into the tax threshold each year until the freeze ends in April 2031 – if it indeed does end and hasn’t been extended again by that time – and by then the Government will have collected billions of pounds worth of extra IHT from the taxpayer.
If you want to find out more, why not give us a call on 0333 323 9065 or book a free non-committal initial consultation with one of our chartered financial advisers to find out how can help.
Arrange a free initial consultation
The Financial Conduct Authority (FCA) does not regulate cash flow planning, tax or estate planning.
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information contained in this article is based on our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
What should I do with my pension lump sum?
If you have already retired, or if you are approaching this milestone, you have probably been thinking about what you should do with your pension lump sum. Should you take it now so you can spend or gift it, should you leave it where it is to maximise the potential tax-free return or should you withdraw it in stages to provide a tax efficient income?
The answer will likely depend on your personal circumstances and your overall retirement objectives. Before you take anything, make sure you understand what type of pension you have, when you can access it, how tax works, and what taking money out now could mean for the rest of your retirement.
For most people with a defined contribution pension, you can access your lump sum from the age of 55 (rising to 57 from April 2028) and you can normally take up to 25% tax free, subject to the lump sum allowance of £268,275.
What is a defined contribution pension?
A defined contribution (DC) pension is a pension where you build up a pot of money over time through your and your employer's contributions, tax relief from the government, and investment growth. At the point of your retirement, you will not necessarily receive a guaranteed income, but instead, you will have an amount of money you can withdraw and spend flexibly to meet your life expenditure requirements. This means the responsibility is on you to make sure any withdrawals are sustainable so that this money will last for the rest of your life.
When it comes to how you might use your defined contribution pension, you might take some tax-free cash, leave the rest invested, draw income gradually, or use some or all of it to buy a guaranteed income in the form of an annuity. These decisions can be daunting as you are effectively making decisions that will impact you for the rest of your life, and this is where having a solid financial plan can support the decision-making process.
What type of pension do I have?
This is the first question to answer before doing anything with your lump sum because your options depend heavily on the pension type you have. And in some cases, you may have a mix of different types of pensions.
Broadly, most people will have either a defined contribution pension or a defined benefit (DB) pension, which is often called a final salary pension. A defined benefit pension typically pays a secure income for life based on your salary and length of service, rather than giving you a pension pot to manage yourself, providing a level of security not automatically achieved from a defined contribution pension. Defined benefit pensions can come with a decision whether to draw a tax-free lump sum in return for a reduced level of income. This can be an attractive option to pay for a nice retirement holiday, or to give to your children, but again, this decision should be made with the long-term in mind.
One way to understand the type of pension you hold, is to review the paperwork you have received from your provider. If your statement refers to a projected pot value, fund choices, or investment performance, it is likely a defined contribution pot. If it talks about an annual income payable at a normal retirement age based on service and salary, it is more likely defined benefit. Many people will have more than one pension, and it is not unusual to have a mix. That is why it is worth checking each scheme individually rather than assuming they will all provide a retirement income in the same way.
When can I take money from my pension?
For private pensions, the earliest age you can usually take money is 55 and this is set to rise to 57 from April 2028. In some cases, you may be able to access benefits earlier because of ill health, but for most savers, the normal minimum pension age applies. Importantly, reaching the age when you can access your pension does not mean you have to take it straight away. Some retirees may benefit from waiting if they do not yet need the money, because leaving the pension untouched can give investments more time to grow and delay the tax decisions that come with withdrawals.
This is where the real decision starts. If you need cash to clear expensive debt, support your lifestyle, or create a buffer in retirement, taking a lump sum could make sense. If you are still working, still contributing, and do not need the money yet, rushing to take it can be a costly decision. A pension is often one of the most tax efficient places to keep long-term retirement savings, so taking cash just because you can, is not always the best move.
Am I taxed on my pension?
Usually, yes, at least on part of it. Most people can take up to 25% of their defined contribution pension tax-free, subject to an overall tax free cash lump sum allowance of £268,275. The remaining 75% is usually taxable as income when drawn. That means the amount of tax you pay depends on how much you withdraw in that tax year and what other income you already have. For the 2026/27 tax year, the standard Personal Allowance is £12,570, basic rate tax is charged on the next £37,700, and the higher rate tax applies to the next £74,870 for England, Wales, and Northern Ireland.
This is why taking your whole pension in one go can result in a nasty surprise. Even if 25% is tax-free, the taxable balance may push you into a higher or additional rate band in that year (or potentially reduce or remove your personal allowance for income over £100,000). Providers also often use a temporary or emergency tax code on the first payment, which can result in too much tax being deducted upfront. In some cases, you can reclaim overpaid tax from HMRC rather than waiting until the end of the tax year.
How can I take money from my defined contribution pension?
You usually have a few main routes. One option is to take up to 25% tax free and leave the rest invested in a drawdown scheme, which essentially is an investment that you draw an income from, taking taxable income only when you need it. This can suit people who want flexibility and are comfortable with investment risk, but it does mean your money remains exposed to market ups and downs and there is no guarantee it will last for life.
Another option is to take up to 25% tax free and use the rest to buy an annuity, which gives you a guaranteed income for the rest of your life. This can be attractive if certainty matters more to you than flexibility. The trade-off is that once an annuity is set up, you cannot reverse the decision, and the rate you secure depends on market conditions and your circumstances at the time.
You can also take your pension as one or more lump sums. In practice, that can mean taking the whole pot in one payment or drawing cash out in stages. This can work well if you want control, but it needs care. Large withdrawals can create unnecessary tax burdens, and once money leaves the pension it loses some of the protection and tax advantages it had while inside the pension account wrapper.
Can I choose more than one way to take my money?
Yes, and for many people that is where the best answer lies. You do not always have to pick a single option and stick with it. You might take some tax-free cash for short term needs, leave part of the pot invested for later, and use another part to buy guaranteed income. If you have more than one pension pot, you can also use different options for different pensions. That can give you a better balance between flexibility, security, and tax efficiency.
What if I am still working?
So far, we have just focused on planning ahead for retirement, but what if you are still working and have a requirement or preference to draw from your pension? In this scenario, just drawing your tax-free cash allowance will not typically restrict the amount that you can contribute to a pension in the future, but taking taxable income flexibly often does. This activates the Money Purchase Annual Allowance, which reduces your annual pension contribution allowance from £60,000 to £10,000, which can matter a great deal if you are still working or may want to keep contributing.
Another important consideration is HMRC’s ‘Tax-Free Cash Recycling Rules’. These rules say you cannot take a tax-free lump sum from your pension with the intention of paying it back in to gain further tax relief. While this sounds straightforward, it can become more complex in practice and requires careful thought. A common example is where someone plans to draw a tax-free lump sum while they are still working, perhaps to repay their mortgage. Once the mortgage is cleared, they may find they have extra disposable income and decide to increase contributions to their workplace pension.
Although the withdrawal and the increased contributions may appear unrelated, they could still be viewed as linked under the rules. This means the arrangement could breach HMRC guidelines and potentially lead to a significant tax charge.
If you are considering a similar approach, it’s sensible to speak with a financial adviser to ensure you don’t face any unexpected tax consequences.
Speak to a pension specialist today
In most cases, before making any irreversible decisions it is best to pause and look at the bigger picture. Consider what income you will need, what secure income you already have, whether you are still working, how much tax you may pay, and whether taking cash now could reduce your options later. A pension lump sum can be useful, but it should support your retirement plan rather than drive it.
A good pension specialist can help you work through the options and considerations clearly, while helping to guide you through this decision-making process to ensure the action taken is in line with your requirements, not only now, but for the rest of your life. Most importantly, this can help you avoid turning a valuable pension into an avoidable tax bill or a short-term fix that weakens your long-term financial security.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.
The information is based upon our understanding of legislation, whether proposed or in force, and market practice at the time of writing. Levels, bases and reliefs from taxation may be subject to change.
The value of investments can go down as well as up, you may not get back what you originally invested. The FCA does not regulate tax, estate or cash flow planning.
Inflation drops to 2.8%... but can it last?
The rate of inflation in the UK has dropped more than anticipated to 2.8% in the year to April, according to the latest figures from the Office for National Statistics (ONS). This is a notable drop from the 3.3% figure in the year to March.
Inflation continued to ease even as fuel costs climbed in the wake of the Iran conflict.
Data from the ONS showed petrol averaged 156.8p per litre last month, marking its highest level since November 2022. Diesel prices also jumped by more than 30p in April, pushing the average cost up to 190p per litre, the highest recorded since July 2022.
According to the RAC, petrol prices have continued to rise in May, reaching a new peak of 158.52p per litre on Tuesday.
So why has inflation fallen this time, and will it stick?
According to the ONS, energy costs had fallen thanks to a combination of reduced wholesale prices and the government’s energy bill support measures introduced before the Iran conflict began.
But economists are warning that inflation is likely to be on the rise again soon, potentially hitting around 4% by the end of the year, with ongoing tensions in the Middle East continuing to drive up global prices.
It’s also important to note that it can often take about a year for food supply cost changes to truly be reflected in food prices in the UK, so there are likely to be some price shocks as the economy catches up to the supply chain issues caused by the conflict.
What is inflation and how is it measured?
Inflation is a measure of how the prices of goods and services have increased over time. Goods are tangible items sold to customers, such as food, while services are tasks performed for the benefit of recipients, such as a haircut. Generally, this increase is measured by considering the cost of things today compared to how much they cost a year ago. The average increase between these prices is demonstrated in the inflation rate.
Rising inflation directly affects the cost of living. For example, if the price of a bottle of milk is £1, and inflation is increasing by 5%, then your bottle of milk will cost you 5p more. Or, in other words, the spending power of your money has decreased by 5%.
Ideally, the Government wants to keep inflation low and stable. The general mandated target for the Bank of England is 2%.
Anything significantly above or below this target is thought to cause issues for the economy.
The cost of living surged in recent years, with inflation peaking at 11% in 2022 - way above the Bank of England's 2% target, partly due to the increase in energy prices following Russia's invasion of Ukraine.
While the rate has dropped, falling inflation does not mean the goods and services are coming down in price overall, it is just that they are rising at a slower pace.
Our chartered financial advisers are expert and unbiased, meaning that they can give whole of market advice, and so are best placed to give you a plan tailored exactly to your personal financial goals.
If you’d like to know more, request a free non-committal initial consultation with one of our team or give us a call on 0333 323 9065 and get in touch.
Arrange your free initial consultation
This article is intended for general information only, it does not constitute individual advice and should not be used to inform financial decisions.